Feeds:
Posts
Comments

Archive for the ‘Stocks’ Category

Robert L. Chapman, Jr. recently resigned as Chief Executive Officer of EDCI Holdings Inc (NASDAQ:EDCI) to focus on Chapman Capital in what he says “may be the most dynamic passive investment environment of a lifetime.” In the announcement to the market, said Chapman in his inimitable style:

Having ablated and amputated certain incontinent expenditures, and set EDCI on a prudent, judicious course of balanced scrutiny of acquisition vs. recapitalization, in addition to orchestrating EDC’s Blackburn-Hannover consolidation plan, I avidly look forward to shifting all my attention to Chapman Capital and related investment portfolios during what may be the most dynamic passive investment environment of a lifetime.

We’ve written previously about Chapman’s fondness for “asset-rich companies with battered stock prices,” which sees him frequently operating in the universe of stocks trading below liquidation value. We think it’s a good sign for sub-liquidation value investors like us that Chapman is back.

Read the announcement here:

EDCI Holdings, Inc. Announces Resignation of Robert L. Chapman, Jr. as Chief Executive Officer

NEW YORK, July 2 /PRNewswire-FirstCall/ — EDCI Holdings, Inc. (Nasdaq: EDCI – News; “EDCI”), the holding company for Entertainment Distribution Company, Inc., the majority shareholder of Entertainment Distribution Company, LLC (“EDC”), a European provider of supply chain services to the optical disc market, today announced the resignation of Robert L. Chapman, Jr. as Chief Executive Officer. Mr. Chapman, who also has resigned from EDCI’s Board of Directors, had replaced Interim Chief Executive Officer Clarke H. Bailey, who himself now replaces Mr. Chapman as EDCI Chief Executive Officer and EDC Interim Chief Executive Officer, effective July 2, 2009.

Mr. Chapman commented, “When I accepted the invitation six months ago from EDCI and EDC’s Boards of Directors to lead these companies through the difficult industry and global recessionary environment that characterized the first half of 2009, I conceived and preached the mantra of ‘Don’t Burn It & Don’t Blow It’ as it related to preserving EDCI’s sacred cash holdings. Furthermore, the seemingly constant headwinds of operating in the disc manufacturing and distribution business, with Universal Music Group as EDC’s supermajority customer, required immediate countermeasures to bolster EDC’s liquidity and longevity. Having ablated and amputated certain incontinent expenditures, and set EDCI on a prudent, judicious course of balanced scrutiny of acquisition vs. recapitalization, in addition to orchestrating EDC’s Blackburn-Hannover consolidation plan, I avidly look forward to shifting all my attention to Chapman Capital and related investment portfolios during what may be the most dynamic passive investment environment of a lifetime.”

Horace Sibley, Chairman of EDCI’s Governance Committee, commented, “In the CEO position at EDCI and EDC, Bob has demonstrated the fortitude to make tough decisions to solve tough problems. Over just a few months, Bob has reformulated the culture and streamlined the cost structure in ways that should benefit both EDCI and EDC for years to come. While the Boards of both EDCI and EDC were disappointed to learn of Bob’s decision to re-focus all his energy on his investment business, there can be no doubt that Clarke Bailey, Chairman of the Board, is the ideal leader to whom the baton should be handed to serve as CEO once again.”

Mr. Chapman joined EDCI’s Board of Directors as an independent director in November 2007, and is the Managing Member of Chapman Capital L.L.C., an investment advisor focusing on activist investing and turnaround investing. Prior to founding Chapman Capital in 1996, Mr. Chapman co-managed the Value Group within Scudder Stevens & Clark, which followed employment with NatWest Securities USA and Goldman, Sachs & Co.

Mr. Bailey joined EDCI’s Board of Directors in December 1990. From September 2008 to January 2009, he served as EDCI’s Interim Chief Executive Officer, after serving as EDCI’s Chief Executive Officer from October 2003 to November 2006 and from December 1990 to March 1994. Mr. Bailey has served as Chairman EDCI’s Board of Directors since October 1999, following his service as EDCI’s Vice Chairman from November 1992 to June 1996. Currently, Mr. Bailey serves as a director on the Boards of Directors of both Iron Mountain Incorporated and ACT Teleconferencing, Inc.
Read Full Post »

Soapstone Networks Inc (NASDAQ:SOAP) has announced the sale of its software assets to Extreme Networks, Inc. (NASDAQ: EXTR). The sale price was not disclosed in the announcement, but may have been less than $5M.

We opened the position in SOAP on February 2nd (see our post archive here) because it was trading well below our estimate of its net cash value. An activist investor, Mithras Capital, had disclosed an 8.7% holding and called on the company to liquidate. After some urging on Mithras Capital’s part, management acceded to the request and announced a liquidation. SOAP stockholders approved the liquidation of the company on July 28 and received a special dividend of $3.75 per share the next day. Based on our $2.50 purchase price, the $3.75 per share special dividend returned our initial capital plus 50%. At yesterday’s close, the $0.46 stub represents an additional 18% on our initial purchase price for a total return to date of 68%. Management estimates the final distribution will be between $0.25 and $0.75 per share, which means the stub is trading under the $0.50 midpoint of the distribution range.

As we demonstrated in an earlier post, Valuing the SOAP stub, determining the proceeds from the asset sale is key in estimating the final pay out figure. Two categories account for the majority (80%) of the difference between the upper and lower estimates of the final distribution:

  1. Real Estate and Equipment Lease termination costs: The lower bound of the range is -$5.4M and the upper bound is -$1.6M, which is a difference of around $3.8M or $0.25 per share.
  2. Proceeds from the sale of Assets: The lower bound of the range is $0.1M and the upper bound is $2.3M, which is a difference of around $2.2M or $0.14 per share.

If the sale price is in fact closer to $5m, SOAP management seems to have significantly underestimated the range for Proceeds from the sale of Assets. At its close yesterday of $0.46, the SOAP stub might become an attractive investment opportunity if we can get some certainty around the actual figure for the proceeds from the sale of the software assets.

The press release is set out below (via CNNMoney):

Extreme Networks Acquires Soapstone Networks Provisioning and Service Assurance Software

Purchase of Ethernet Service Aware Software and Control Plane Underscores Focus on Simplification of Carrier Ethernet Deployments

August 10, 2009: 08:00 AM ET

Extreme Networks, Inc. (NASDAQ: EXTR) today announced the purchase of the software assets of Soapstone Networks, Inc (PINKSHEETS: SOAP). The Soapstone Networks software serves as a foundation for provisioning and service assurance for carrier Ethernet networks.

The transaction transfers ownership of the Soapstone Networks software control plane and service aware provisioning system to Extreme Networks®, enabling Extreme Networks to simplify the service provider’s job of provisioning and maintaining Ethernet services for their subscribers.

“The addition of the software assets from Soapstone Networks into the Extreme Networks intellectual property portfolio continues our commitment to carrier Ethernet,” said Glenn Weinberg, Vice President and General Manager, Extreme Networks Software Business Unit. “The unique provisioning and service aware capabilities of the Soapstone Networks software will enable Extreme Networks to deliver a more complete, extensible solution to carrier Ethernet service providers.”

The Soapstone Networks software will be integrated into the Extreme Networks EPICenter® Network Management System, providing a service level view, provisioning and management of carrier Ethernet networks and protocols including Provider Bridging (PB), Provider Backbone Bridging (PBB), Provider Backbone Bridging with Traffic Engineering (PBB-TE), Ethernet Access Protection Switching (EAPS) and Virtual Private Line (VPLS).

Hat tip JM.

[Full Disclosure:  We have a holding in SOAP. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

The Official Activist Investing Blog has published its list of activist investments for July:

Ticker Company Investor
ANR Alpha Natural Resources Duquesne Capital Management
ASP American Strategic Income Portolio Inc SIT Investment Associates
ASTC Astrotech Corp Trace Capital
ASUR Asure Software Red Oak Partners
BASI Bioanalytical Systems Peter Kissinger
BEE Strategic Hotels & Resorts Vector Holdings
BTIM.OB Biotime Inc. Broadwood Partners
CNBC Center Bancorp Lawrence Seidman
CNSO.OB CNS Response Inc Leonard Brandt
ENTU Entrust Inc. Arnhold & S. Bleichroeder Advisers
ENTU Entrust Inc. Douglas Schloss
ENZN Enzon Pharmaceuticals Inc. DellaCamera Capital Management
HBRF.OB Highbury Financial Peerless Systems
HBRF.OB Highbury Financial Talon Asset Management
HPOL Harris Interactive Inc Mill Road Capital
IFLO I-Flow Corp Discovery Capital
LGF Lions Gate Entertainment MHR Group
LVWR LiveWire Mobile Inc Karen Singer/Lloyd Miller
MIN MFS Intermediate Income Trust Karpus Management
MZF MBIA Capital Claymore Man Dur Inv Grd Muni Fund Western Investment
NLCI Nobel Learning Communities Discovery Capital
PLCE The Children’s Place Retail Stores, Inc Ezra Dabah
PPM Investment Grade Municipal Income Fund Western Investment
PTYA.PK Penn Treaty American Corp Atlas Capital Management
PTYA.PK Penn Treaty American Corp Bedford Oak Partners
SLA American Select Portfolio Inc SIT Investment Associates
TESS Tessco Technologies Discovery Equity Partners
TOH Hicks Acquisition Co Bulldog Investors
TXI Texas Industries Inc Shamrock Activist Value Fund
UAHC United American Healthcare Corp. Lloyd Miller
UAHC United American Healthcare Corp. Strategic Turnaround Equity Partners

Read Full Post »

Forward Industries Inc (NASDAQ:FORD) has filed its quarterly report for the period ended June 30, 2009.

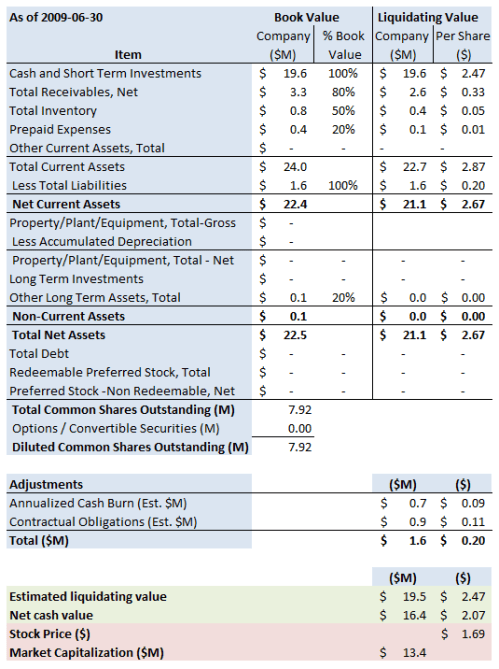
We started following FORD (see our post archive here) because it was trading at a discount to its net cash and liquidation values, although there was no obvious catalyst. Management appeared to be considering a “strategic transaction” of some kind, which might have included an “acquisition or some other combination.” Trinad Management had an activist position in the stock, but had been selling at the time we opened the position and only one stockholder owned more than 5% of the stock. The stock is up 17.4% since we opened the position to close yesterday at $1.69, giving the company a market capitalization of $13.4M. Following our review of the most recent 10Q, we’ve slightly reduced our estimate of the liquidation value to $19.5M or $2.47 per share.

The value proposition updated

FORD continues to face difficult trading conditions, writing in the most recent 10Q:

Trends and Economic Environment: We believe that the deteriorating economic conditions, rising unemployment, tight credit markets, and heightened uncertainty in financial markets during the past 18 months have adversely impacted discretionary consumer spending, including spending on the types of electronic devices that are accessorized by our products. We expect this challenging business environment to continue in the foreseeable future.

The company had a slightly better quarter than the preceding one, but still burned through nearly $0.3M of cash (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

FORD Summary 2009 06 30

Summary balance sheet adjustments

We’ve made the following adjustments to the balance sheet estimates (included in the valuation above):

  • Cash burn: We’ve got no real idea about FORD’s prospects. Its cash burn over the last quarter was around $0.3M. That was made up of $0.2M of cash used in operations and $0.1M cash used in investment activities. If we assume, as management has, that the company will face a similarly tough operating environment over the next 12 months, we estimate cash burn of around $0.7M.
  • Off-balance sheet arrangements: According to FORD’s most recent 10Q, it has no off-balance sheet arrangements.
  • Contractual obligations: FORD’s contractual obligations are minimal, totalling $0.9M.

Possible catalysts

FORD’s President and Acting Chairman, Mr. Doug Sabra, said in the letter to FORD shareholders accompanying the notice of annual shareholders’ meeting, that in 2008 “management began to implement operational and strategic initiatives in order to put [FORD]’s business on a stronger, more sustainable footing. …  This past August we retained an outside consultant to assist us in vetting possible partners for a strategic transaction.” It seems that the “strategic transaction” might include a “possible acquisition or other combination that makes sense in the context of [FORD’s] existing business, without jeopardizing the strong financial position that we have worked so hard to build.” FORD’s focus on a “strategic transaction” is a positive, in our view, although our vast preference is for a sale of the company, buyback, special dividend or return of capital over an acquisition.

Any transaction will require the consent of FORD’s board. While it has a free float of around 92%, the company’s so-called “Anti-takeover Provisions” authorize the board to issue up to 4M shares of “blank check” preferred stock. From the 10Q:

The Board of Directors has the authority and discretion, without shareholder approval, to issue preferred stock in one or more series for any consideration it deems appropriate, and to fix the relative rights and preferences thereof including their redemption, dividend and conversion rights.

Conclusion

At its $1.69 close Friday, FORD is trading at a substantial 46% discount to its $2.47 per share liquidation value and $2.07 per share net cash value. While there’s no obvious catalyst in the stock at this stage, management’s consideration of a “strategic transaction” is a positive. The risk to this position is management spending the cash on an acquisition. We think a far better use of the company’s cash is a buyback, special dividend or return of capital. Another concern is Trinad Management exiting its activist position in the stock. Those concerns aside, we’re going to maintain our position because still looks cheap at a discount to net cash.

[Full Disclosure:  We have a holding in FORD. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

CoSine Communications Inc (OTC:COSN) is an interesting little pink sheet play: a cash box controlled by activist investor Steel Partners. Steel Partners, whose holdings we recently covered in the Catalyst Investment Research on Steel Partners II Investment Portfolio post, owns 44.9% of the stock and sits on the board. At its $1.75 close yesterday, COSN’s market capitalization is just $17.7M. We estimate the net cash value to be around 26% higher at $22.2M or $2.20 per share. The net cash value has remained stable through 2006, 2007, 2008 and 2009, while the stock has halved from $3.50 to $1.75 for no fundamental reason that we can identify. Usually a discount like that wouldn’t get us excited, but this is not a liquidation play. COSN is an acquisition play with Steel Partners in the driver’s seat (the company also has substantial NOLs). We’re adding it to the Greenbackd Portfolio for those reasons.

About COSN

From the most recent 10Q:

[COSN] was incorporated in California on April 14, 1997 and in August 2000 was reincorporated in the State of Delaware. Our current business strategy is to enhance stockholder value by pursuing opportunities to redeploy our assets through an acquisition of one or more operating businesses with existing or prospective taxable earnings that can be offset by use of our net operating loss carry-forwards (“NOLs”). No assurance can be given that we will find suitable candidates, and if we do, that we will be able to utilize our existing NOLs.

We were a provider of carrier network equipment products and services until the fourth quarter of fiscal year 2004 during which time we discontinued our product lines, took actions to lay off most of our employees, terminated contract manufacturing arrangements, contractor and consulting arrangements and various facility leases, and sold, scrapped or wrote-off our inventory, property and equipment. In July 2005, our board of directors approved our strategy of redeploying our existing resources to identify and acquire new business operations. In 2006, we sold the remaining assets of our carrier network products business with the sale of our patent portfolio and the rights to the related intellectual property. During 2006, we also completed the wrap-up of our carrier services business, providing customer support services for our discontinued products through December 31, 2006, at which time we terminated all customer support offerings. Effective July 1, 2007, we engaged SP Corporate Services LLC to provide all of our executive, financial and administrative support service, rent and personnel requirements and, as a result, we no longer have any employees.

The value proposition

The valuation on COSN is straight-forward: It has around $23m in cash and short-term investments, $0.2M in liabilities and 10.1M shares outstanding. We’ve set out the valuation below in the usual manner (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

COSN Summary 2009 03 31

Balance sheet adjustments

We’ve made the following adjustments to the balance sheet estimates above:

  • Cash burn: The company used $0.1M in cash in the second quarter, which we’ve annualized to $0.6M. $0.6M might be too conservative.
  • Off-balance sheet arrangements and contractual obligations: According to COSN’s 10Q, it has no off-balance sheet arrangements.

NOLS

A quick primer on net operating loss carry-forwards (“NOLs”) from the most recent 10K:

NOLs may be carried forward to offset federal and state taxable income in future years and eliminate income taxes otherwise payable on such taxable income, subject to certain adjustments. Based on current federal corporate income tax rates, our NOLs and other carry-forwards could provide a benefit to us, if fully utilized, of significant future tax savings. However, our ability to use these tax benefits in future years will depend upon the amount of our otherwise taxable income. If we do not have sufficient taxable income in future years to use the tax benefits before they expire, we will lose the benefit of these NOLs permanently. Consequently, our ability to use the tax benefits associated with our substantial NOLs will depend significantly on our success in identifying suitable acquisition candidates, and once identified, successfully consummating an acquisition of these candidates.

Additionally, if we underwent an ownership change, the NOLs would be subject to an annual limit on the amount of the taxable income that may be offset by our NOLs generated prior to the ownership change. If an ownership change were to occur, we may be unable to use a significant portion of our NOLs to offset taxable income. In general, an ownership change occurs when, as of any testing date, the aggregate of the increase in percentage points is more than 50 percentage points of the total amount of a corporation’s stock owned by “5-percent stockholders,” within the meaning of the NOLs limitations, whose percentage ownership of the stock has increased as of such date over the lowest percentage of the stock owned by each such “5-percent stockholder” at any time during the three-year period preceding such date. In general, persons who own 5% or more of a corporation’s stock are “5-percent stockholders,” and all other persons who own less than 5% of a corporation’s stock are treated, together, as a single, public group “5-percent stockholder,” regardless of whether they own an aggregate of 5% of a corporation’s stock.

The amount of NOLs that we have claimed has not been audited or otherwise validated by the U.S. Internal Revenue Service (“IRS”). The IRS could challenge our calculation of the amount of our NOLs or our determinations as to when a prior change in ownership occurred and other provisions of the Internal Revenue Code may limit our ability to carry forward our NOLs to offset taxable income in future years. If the IRS was successful with respect to any such challenge, the potential tax benefit of the NOLs to us could be substantially reduced.

According to the 10K, as of December 31, 2008, COSN had federal NOLs of approximately $353M, which begin to expire in 2018 if not utilized and state NOLs of approximately $213M, which will begin to expire in 2009 if not utilized. The NOLs have a substantial value as a tax shield should COSN acquire a business with taxable earnings, but assessing that value is beyond us.

Catalyst

Steel Partners’ most recent 13D filing sets out its 44.9% holding. Steel Partners’ strategy is to use COSN’s cash to acquire a business with taxable earnings that can be offset by the NOLs. From the 10Q:

Redeployment Strategy and Liquidity

In July 2005, after a comprehensive review of strategic alternatives, our board of directors approved a strategy to redeploy our existing resources to identify and acquire one or more new business operations with existing or prospective taxable earnings that can be offset by use of our NOLs.

Ordinarly, we would prefer a return of cash to the acquisition of a business. This situation is different from the usual case because Steel Partners’ business is investment, and so we think the risk that they might make a bad investment is low. That said, there’s no assurance that they will find a suitable candidate, or if they do, that COSN will be able to use the NOLs.

Conclusion

COSN presents an opportunity to invest alongside Steel Partners at a 26% discount to net cash in a company with substantial NOLs. We think it’s too good to pass up, so we’re adding it to the Greenbackd Portfolio. The stock is very thinly traded, so take care getting set.

COSN closed yesterday at $1.75.

The S&P500 closed yesterday at 997.08.

[Full Disclosure:  We do not have a holding in COSN. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Hat tip FF.

Read Full Post »

VaxGen Inc (OTC:VXGN) has released its quarterly report for the period ended June 30, 2009.

We’ve been following VXGN (see our post archive here) because it is trading at a substantial discount to its net cash position, has ended its cash-burning product development activities and is “seeking to maximize the value of its remaining assets through a strategic transaction or series of strategic transactions.” If the company is unable to identify and complete an alternate strategic transaction, it proposes to liquidate. One concern of ours has been a lawsuit against VXGN by its landlords, in which they sought $22.4M. That lawsuit was dismissed in May, so the path for VXGN to liquidate has now hopefully cleared.

VXGN has now also attracted the attention of BA Value Investors, which has disclosed an activist holding and called on VXGN to “act promptly to reduce the size of the board to three directors; reduce director compensation; change to a smaller audit firm; terminate the lease of its facilities; otherwise cut costs; make an immediate $10 million distribution to shareholders; make a subsequent distribution of substantially all the remaining cash after settling the lease termination; distribute any royalty income to shareholders; and explore ways to monetize the public company value of the Issuer and use of its net operating losses.”

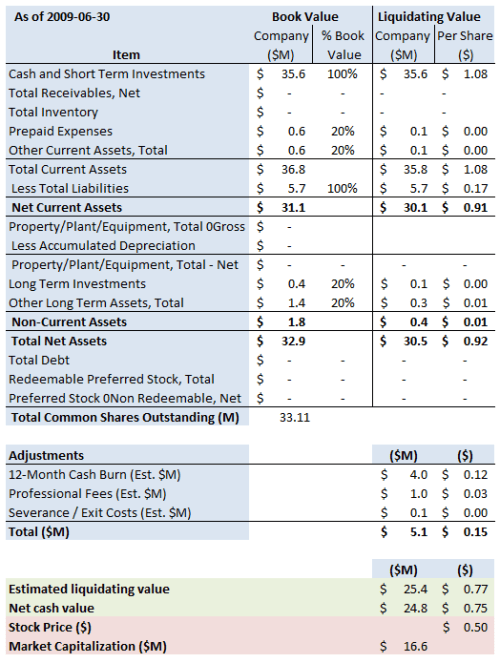
At its $0.50 close yesterday, VXGN has a market capitalization of $16.6M. We last estimated the company’s liquidation value to be around $26.5M or $0.80 per share. Following our review of the most recent quarterly report, we’ve slightly reduced our estimate to $25.4M or $0.77 per share. VXGN has other potentially valuable assets, including a “state-of-the-art biopharmaceutical manufacturing facility with a 1,000-liter bioreactor that can be used to make cell culture or microbial biologic products” and rights to specified percentages of future net sales relating to its anthrax vaccine product candidate and related technology.

The value proposition updated

VXGN has taken steps to minimize its cash burn, reducing its workforce to three employees, terminating its anthrax and smallpox development activities and selling the assets related to its anthrax product candidate. The company’s value rests on its vestigial holding of cash and equivalents (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

VXGN Summary 2009 6 30 v2Balance sheet adjustments

We’ve made the following adjustments to the balance sheet estimates above:

  • Cash burn: The company used $1.1M in cash in the second quarter, down from $2.1M in the first quarter. We have included cash burn of $4M in our estimate for the year. We have also assumed professional fees and termination payments of $1.1M.
  • Off-balance sheet arrangements and contractual obligations: According to VXGN’s 10Q, it has no off-balance sheet arrangements.

The lawsuit against VXGN by its landlords, in which they sought $22.4M, has been dismissed:

In February 2009, a lawsuit was filed against us in the Superior Court of California for the County of San Mateo by plaintiffs, Oyster Point Tech Center, LLC. The plaintiffs generally allege that we defaulted on our lease for our facility located at 349 Oyster Point, South San Francisco, California. The complaint seeks possession of the premises and the balance of the lease plus unpaid rent and expenses totaling $22.4 million, as well as an award of plaintiffs’ attorneys’ fees and costs. Our biopharmaceutical manufacturing facility is located in the leased premises that are the subject of the dispute. At a February hearing, the court denied the writ and the temporary protective order sought by landlord. In May 2009, the lawsuit was dismissed.

Conclusion

At its $0.50 close yesterday, VSGN has a market capitalization of $16.6M. We estimate the net current asset / liquidation value to be around 74% higher at $25.4M or $0.77 per share. VXGN has other potentially valuable assets, including rights to a portion of future net sales on its anthrax technology and a state-of-the-art biopharmaceutical manufacturing facility. One concern has been a lawsuit brought by the landlord against the company, so it is encouraging that the lawsuit has been dismissed. With its stock at a substantial discount to its net current asset / liquidation value, its cash-burning product development activities at an end and a proposal to identify and complete an alternate strategic transaction or liquidate, we think VXGN is still a good prospect, and we’re going to maintain our position.

[Full Disclosure: We have a holding in VXGN. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Soapstone Networks Inc (NASDAQ:SOAP) closed Friday at $0.495 following the payment last week of a $57.5M or $3.75 per share special dividend. The company estimates the final distribution at between $0.25 and $0.75 per share. The higher end of the distribution range represents a ~50% upside from Friday’s close, so we’re going to do some work now to determine whether we hold on to the stub, buy some more or close out the position.

We opened the position in SOAP on February 2nd (see our post archive here) because it was trading well below our estimate of its net cash value. An activist investor, Mithras Capital, had disclosed an 8.7% holding and called on the company to liquidate. After some urging on Mithras Capital’s part, management acceded to the request and announced a liquidation. SOAP stockholders approved the liquidation of the company last week and were paid a special dividend of $3.75 per share. Based on our $2.50 purchase price, the $3.75 per share special dividend returns our initial capital plus 50%. At the Friday close, the $0.495 stub represents an additional 20% on our initial purchase price for a total return to date of 70%. Management estimates the final distribution will be between $0.25 and $0.75 per share, which means the stub is trading at a fraction under the midpoint of the distribution range.

The value proposition for the SOAP stub

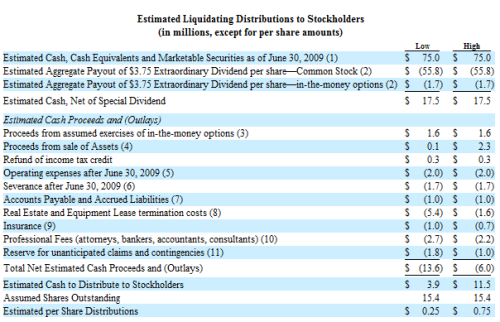
Following the payment of the special dividend, SOAP has cash of around $17.5M or a little over $1.00 per share. The basis for SOAP management’s calculation of the $0.25 and $0.75 per share distribution is set out below (extracted from the Preliminary Proxy Statement):

SOAP Estimated Liquidating Distributions

(The table above has been modified from the original to fit this space)

(1) Estimated balance is net of cash used for the period April 1, 2009 through June 30, 2009 for estimated operating expenses ($4.2 million), severance costs ($1.7 million) and accounts payable and accrued liabilities ($1.5 million), partially offset by interest income ($0.1 million).

(2) Estimated Extraordinary Dividend payments of $55.8 million are associated with 14,886,107 shares of our common stock outstanding as of June 16, 2009 and Extraordinary Dividend payments of $1.7 million are associated with 460,828 shares of our common stock subject to currently vested options that are in-the-money at $4.13, the per share closing price of our stock on the Nasdaq Global Market on June 16, 2009, which options are assumed to be exercised prior to the dividend payment.

(3) Estimated proceeds from the exercise of currently vested options for 460,828 shares of our common stock that are in-the-money at $4.13, the per share closing price of our stock on the Nasdaq Global Market on June 16, 2009, which options are assumed to be exercised prior to the dividend payment.

(4) Estimated range of cash proceeds from sale of assets, including technology, intellectual property, furniture, fixtures and equipment.

(5) Estimated operating expenses for the period of July 1, 2009 through June 30, 2010 for personnel, facilities and other expenses to conduct our wind up operations but exclusive of all other line items specifically allocated in the table above.

(6) Estimated severance costs for remaining employees involved in the wind up operations.

(7) Estimated accounts payable and accrued liabilities as of June 30, 2009.

(8) Estimated range of cash payments associated primarily with lease and lease related commitments for our headquarters facility.

(9) Estimated range of cash use for the purchase of insurance, including Directors and Officers liability insurance covering the six years from the date of stockholder approval of the plan of dissolution.

(10) Estimated range of cash use for professional fees related to our liquidation and dissolution, as well as ongoing SEC reporting requirements.

(11) Estimated range of cash use for unanticipated claims and contingencies, including potential deductibles and retentions associated with potential insurance claims.

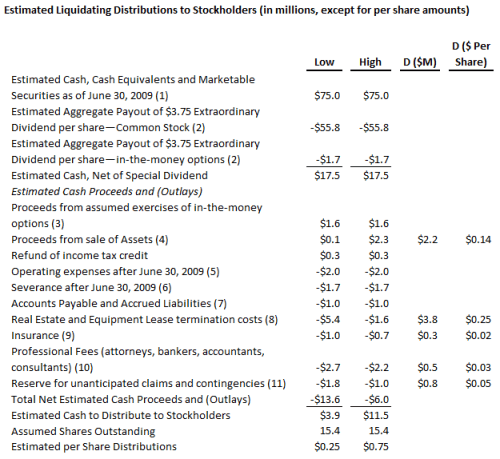
Set out below is an analysis of SOAP management’s estimates, showing the differences between the upper and lower estimates:

SOAP Estimated Liquidating Distributions 2

It becomes clear from the preceding table that two categories account for the majority (80%) of the difference between the upper and lower estimates of the final distribution:

  1. Real Estate and Equipment Lease termination costs: Around $3.8M or $0.25 per share.
  2. Proceeds from the sale of Assets: Around $2.2M or $0.14 per share.

We’ve got no real idea about the likely final figures in either of these categories, which means we won’t be buying any more at this stage. Given that the stock is trading at a fraction under the midpoint of management’s estimate of the final distribution, we’re going to hold on to our remaining stock for the time being and see how it plays out.

[Full Disclosure:  We have a holding in SOAP. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Lamassu Holdings has sent another scorching letter to the board of Ditech Networks Inc (NASDAQ:DITC). In the letter, Lamassu claims that the “decisions of this board have shown a pattern of director entrenchment characterized by prioritizing the interest of its members in the face of poor results at the expense of the shareholders” and has called for shareholders to “receive ample representation on the board.”

We’ve been following DITC (see our archive here) because it is trading below its net cash value with an investor, Lamassu Holdings LLC, disclosing a 9.4% holding in November last year. Lamassu has previously offered to acquire DITC for $1.25 per share in cash. Lamassu says that it “anticipates its due diligence requirement will take no more than two weeks and there is no financing contingency.” Lamassu has now nominated two candidates for election to the board “who are committed to enhancing shareholder value through a review of the Company’s business and strategic direction.” Lloyd I Miller III has also disclosed a 5.9% holding and has come out in support of Mr. Leehealey and Mr. Sansone – the director candidates nominated by Lamassu Holdings for election to the board of directors at the DITC annual meeting – as “candidates who are independent of management and he seeks to encourage greater attention to corporate governance by all members of the Board of Directors.” The stock is up 47.2% from our initial $0.89 to close yesterday at $1.31, giving the company a market capitalization of $34.5M. We last estimated the net cash value at around $32.2M or $1.23 per share and the liquidation value at around $43.4M or $1.65 per share. While the deterioration in value is a concern, Mr. Miller’s support of Lamassu Holding’s director candidates introduces a new element to the position. We’re inclined to hold on to see how the annual meeting plays out.

The press release setting out the text of the open letter from Lamassu Holdings is set out below:

Lamassu Holdings LLC Says Ditech Network’s Board of Directors Benefits at Shareholders’ Expense

Lamassu Holdings LLC files an open letter to the Board of Directors of DITECH NETWORKS, INC. (NASDAQ: DITC)

NEWPORT BEACH, Calif.–(BUSINESS WIRE)–Lamassu Holdings, LLC has sent the following letter to the Board of Directors of Ditech Networks, Inc.

Dear Board of Directors:

The purpose of this letter is to inform you that while you have historically operated with impunity in your role as Directors of Ditech Networks (NASDAQ: DITC – News), going forward your actions will be regarded with a much higher degree of scrutiny. The decisions of this board have shown a pattern of director entrenchment characterized by prioritizing the interest of its members in the face of poor results at the expense of the shareholders. In light of this trend, it is time that the shareholders receive ample representation on the board.

We have taken the time to go through the company’s filing and pull out some of the decisions that were clearly made to benefit the board while adding no value to shareholders. It is worth noting that these decisions were, for the most part, made by the same people who currently serve. We believe these decisions illustrate that, with the exception of Mr. Simpons and Mr. Dramis, all of the currently serving members, including Mr. Harper, Mr. Manoliu, Mr. Sugishita, Mr. Hasler and Mr. Avis, have established a clear pattern of rewarding themselves while shareholders suffer.

In 2003 (see Figure 1), Ditech Networks moved from a policy in which board members were paid in options to one in which they were paid with both cash and options. It is worth noting that during the three years prior to this change, there was a dramatic drop in the equity value of the company. In short, since the options you awarded yourselves were no longer worth anything, you chose to guarantee your compensation regardless of performance.

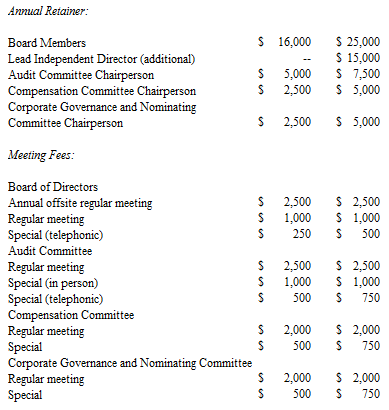
In 2005, after another very difficult period for shareholders, shown in Figure 2, the Board again rewarded itself with pay raises. Beginning on July 15, 2005, non-employee directors began receiving an annual retainer of $16,000; the chairman of the Audit Committee received an additional annual retainer of $5,000; and the chairmen of the Compensation Committee, the Corporate Governance Committee and the Nominating Committee received additional annual retainers of $2,500.

The final insult is the most recent decision made little more than a year ago. As the table below shows, effective May 1, 2008, the Board raised its salaries and several other fees. Ironically, you even actually raised the amount you get paid for “phoning it in” [“Special (telephonic)” line items below]. To put these pay increases in their full context, at the time you granted these raises for yourselves the stock was hitting all time lows on a daily basis and wouldn’t ultimately level off until it reached well below a dollar. In addition, the fundamentals of the company were never as bad as they had been. As a result of poor decisions and failed strategic maneuvers by the Board of Directors, the company had lost millions and millions of dollars. Despite this backdrop, you rewarded yourselves with additional cash at a time when the company apparently didn’t have enough money to buy back its own stock, despite the record low levels.

Lamassu Letter Table

(The table above has been modified from the original to fit this space)

Had compensation increases been used to attract new talent to the Board of Directors and resulted in new directors that brought with them a history of sound business decisions and responsible business practices, then the pay raises could be justified. However, the pay raises were not used for this purpose. Instead, in the face of massive shareholder equity losses and a long list of bad investments, the Board increased its pay with no regard for the massive losses the shareholders were experiencing—losses that were painless for the members of the Board due to their low levels of stock ownership. It is clear that under the current leadership, it has been more financially rewarding to be on the Board than to be a shareholder. For this reason and many others Lamassu has moved to replace two of the current board members with its own nominees. It is our hope that this will both give shareholders a direct voice on the Board, as well as bring about a level of fiduciary responsibility that we believe is currently lacking.

Sincerely,

Lamassu Holdings, LLC

[Full Disclosure:  We do not have a holding in DITC. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Soapstone Networks Inc (NASDAQ:SOAP) has announced that the stockholders have approved the liquidation and dissolution of the company.

We started following SOAP (see our post archive here) because it was trading well below its net cash value with an activist investor, Mithras Capital, disclosing an 8.7% holding in October last year. The stock is up 68.4% from $2.50 when we initiated our position to close today at $4.13, giving SOAP a market capitalization of $61.0M. We last estimated the company’s net cash value to be $80.3M or $5.21 per share. The company has now announced that it proposes to liquidate. It estimates that the total distribution, including an extraordinary cash dividend of $3.75 per share, will be between $4.00 and $4.50 per share. The initial dividend was paid yesterday and the stock trade’s ex-dividend today.

The press release from the company is set out below:

BILLERICA, MA–(Marketwire – July 28, 2009) – Soapstone Networks Inc. (NASDAQ: SOAP), today announced that, at the Company’s annual meeting of stockholders held on July 28, 2009, the stockholders of Soapstone Networks voted to approve the liquidation and dissolution of the Company pursuant to a Plan of Liquidation and Dissolution (the “Plan of Liquidation”).

As previously announced by the Company, in connection with the approval of the Plan of Liquidation, the Company’s Board of Directors has approved an extraordinary cash dividend of $3.75 per share of the Company’s common stock. The dividend will be paid on July 29, 2009 and the Company’s stock will trade ex-dividend commencing July 30, 2009.

The Company intends to file a certificate of dissolution on July 31, 2009 with the Delaware Secretary of State in accordance with the Plan of Liquidation. At the close of business on July 31, 2009, the Company expects to close its stock transfer books and cease recording transfers of shares of its common stock. At that time, the Company’s common stock, and stock certificates evidencing the shares of common stock, will no longer be assignable or transferable on the Company’s books. We have notified Nasdaq OMX of the date we intend to file our certificate of dissolution, and we will seek to delist our shares of common stock as soon as practicable thereafter. In addition, we requested that the Nasdaq Global Market suspend the trading of our common stock effective at the close of business on July 31, 2009. After the Company ceases trading on the Nasdaq Global Market as a result of such suspension, shares of the Company’s common stock held in street name with brokers may be traded in the over-the-counter market on an electronic bulletin board established for unlisted securities such as the OTC Bulletin Board or the Pink Sheets. Such trading will reduce the market liquidity of the Company’s common stock. As a result, an investor would find it more difficult to dispose of, or obtain accurate quotations for the price of the Company’s common stock, if they are able to trade the Common Stock at all.

The Board of Directors has fixed July 31, 2009 as the record date for determining stockholders entitled to receive any future distributions of available assets and as the final date for the recording of stock transfers. Only those stockholders of record as of the close of business on July 31, 2009 (the “Record Stockholders”), will be entitled to such future distributions. The Company anticipates that its first distribution after the July 31, 2009 record date is not likely to occur prior to the first quarter of 2010. Prior to winding up its affairs under Delaware law, the Company intends to make at least one additional liquidating distribution to the Record Stockholders. The Company has not yet established the timing or per share amount of any such distributions.

[Full Disclosure:  We have a holding in SOAP. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Autobytel Inc (NASDAQ:ABTL) has filed its 10Q for the quarter ended June 30, 2009.

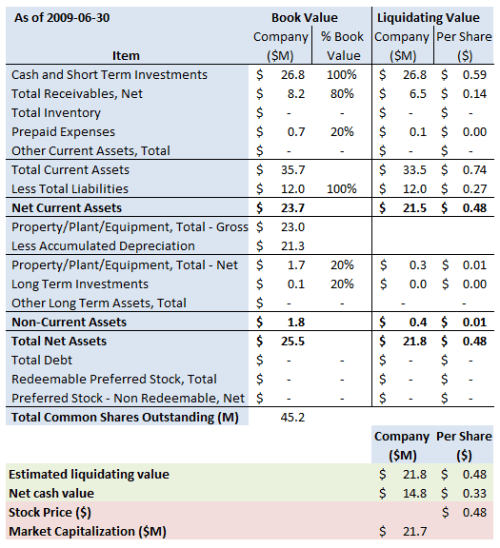
We last estimated ABTL’s liquidation value at $24.3M or $0.54 per share. Following our review of the 10Q, we’ve reduced our estimate to$21.8M or $0.48 per share. The stock closed yesterday at $0.48, which means it’s trading at our estimate of the liquidation value. On that basis, we’re exiting. We opened our position at $0.43, so we’re up 11.6% on an absolute basis. The S&P500 closed yesterday at 979.62, and was at 899.24 when we started following ABTL in December, which means we’re up 2.7% on a relative basis.

Post mortem

We started following ABTL (see our post archive here) because it was trading at a substantial discount to its liquidation and net cash values and Trilogy had filed a 13D notice disclosing a 7.4% holding. Trilogy had also launched a tender offer for ABTL at $0.35 per share. When Trilogy launched its offer, we wrote that we believed that $0.35 per share was only the opening salvo and a higher price was possible if the board terminated the rights plan poison pill. The board rejected the offer out of hand and Trilogy did not make a further offer before the initial offer expired. On expiry of the offer, Trilogy sent a letter to the board saying that it would “continue to evaluate [ABTL’s] business, its cash position, and its operating performance” and called on the board to communicate to its shareholders the break-up value of Autobytel, such that shareholders can determine if that is the best course to maximize value.” That did not eventuate.

ABTL has consumed a great deal of cash over the last years. Its principal sources of liquidity are from proceeds from dispositions of non-core businesses and the patent litigation settlement payments. Our estimate for ABTL’s liquidation value is set out below (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

ABTL Summary 2008 6 30

Conclusion

Our position in ABTL has been a disappointing one, and has dragged down the performance of the portfolio. That aside, we can’t be too unhappy with a slightly positive result in a declining company.

[Full Disclosure:  We do not have a holding in ABTL. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

« Newer Posts - Older Posts »