Feeds:
Posts
Comments

Archive for the ‘Stocks’ Category

VaxGen Inc (OTC:VXGN) has released its quarterly report for the period ended March 31, 2009.

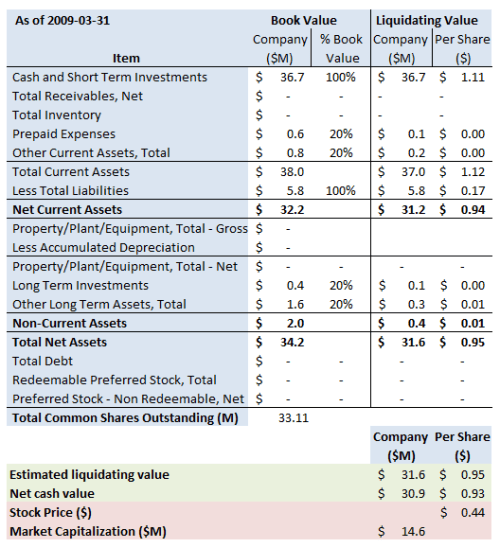
We started following VXGN (see our post archive here) because it was trading at a substantial discount to its net cash position, had ended its cash-burning product development activities and is “seeking to maximize the value of its remaining assets through a strategic transaction or series of strategic transactions.” If the company is unable to identify and complete an alternate strategic transaction, it proposes to liquidate. At its $0.44 close yesterday, VXGN has a market capitalization of $14.6M. We initially estimated the company’s net cash value to be around $27.7M or $0.84 per share. We’ve now reduced that slightly to $26.5M or $0.80 per share. VXGN has other potentially valuable assets, including a “a state-of-the-art biopharmaceutical manufacturing facility with a 1,000-liter bioreactor that can be used to make cell culture or microbial biologic products” and rights to specified percentages of future net sales relating to its anthrax vaccine product candidate and related technology.

The value proposition updated

VXGN has taken steps to minimize its cash burn, reducing its workforce to three employees, terminating its anthrax and smallpox development activities and selling the assets related to its anthrax product candidate. The company’s value rests on its vestigial holding of cash and equivalents (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):
vxgn-summary-2009-3-31

Balance sheet adjustments

We make the following adjustments to the balance sheet estimates above:

  • Cash burn: The company used $2.1M in cash in the first quarter. We have included cash burn of $5M in our estimate for the remainder of the year. We have also assumed termination payments of $0.2M.
  • Off-balance sheet arrangements and contractual obligations: According to VXGN’s 10Q, it has no off-balance sheet arrangements.

One concern is the lawsuit against VXGN by its landlords, in which they seek $22.4M:

In February 2009, a lawsuit was filed against the Company by plaintiffs, Oyster Point Tech Center, LLC. The plaintiffs generally allege that the Company defaulted on the lease on the 349 Oyster Point, South San Francisco facility. The complaint seeks possession of the premises and the balance of lease plus unpaid rent and expenses totaling $22.4 million, as well as an award of plaintiffs’ attorneys’ fees and costs. The Company’s biopharmaceutical manufacturing facility is located in the leased premises that are the subject of the dispute. At a February hearing, the court denied the writ and the temporary protective order sought by landlord. The parties are currently in discussions to achieve an amicable resolution to the matters alleged in the complaint and a negotiated termination of the lease. However, if necessary, the Company intends to vigorously defend against such allegations.

The Company may incur substantial expenses in defending against such claim, and it is not presently possible to accurately forecast the outcome. The Company does not believe, based on current knowledge, that the foregoing legal proceeding is likely to have a material adverse effect on its financial position, results of operations or cash flows. In the event of a determination adverse to the Company, the Company may incur substantial monetary liability and could have a material adverse effect on the Company’s financial position, results of operations or cash flows.

If the lawsuit is succesful, then VXGN has next to no value. We’re taking our guidance from the company, which “does not believe, based on current knowledge, that the foregoing legal proceeding is likely to have a material adverse effect on its financial position, results of operations or cash flows.”

Conclusion

At its $0.44 close yesterday, VSGN has a market capitalization of $14.6M. We estimate the net cash value to be around 82% higher at $26.5M or $0.80 per share. VXGN has other potentially valuable assets, including rights to portion of future net sales on its anthrax technology and a state-of-the-art biopharmaceutical manufacturing facility. One concern is lawsuit by the landlord against the company, but that company states that it does not believe the lawsuit will have a material adverse effect on its financial position.With its stock at a substantial discount to its net cash position, its cash-burning product development activities at an end and a proposal to identify and complete an alternate strategic transaction or liquidate, we think VXGN is a good prospect, and we’re going to maintain our position.

[Full Disclosure: We have a holding in VXGN. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Digirad Corporation (NASDAQ:DRAD) has filed its 10Q for the quarter ended March 31, 2009.

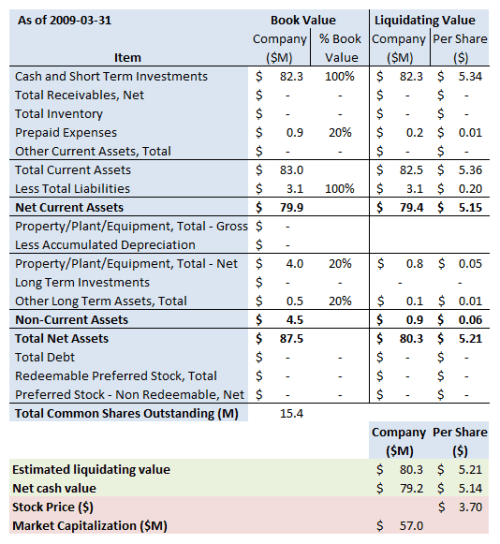
We’ve been following DRAD (see our post archive here) because it is an undervalued asset play with a plan to sell assets and buy back its stock. The stock is up more than 43% since we started following it to close yesterday at $1.26, giving the company a market capitalization of $23.9M. We initially estimated the liquidation value to be around $29.3M or $1.55 per share. After reviewing the Q1 10Q, we’ve left the valuation essentially unchanged at $29.5M or $1.56 per share. The company’s net cash value is around $15.6M or $0.82 per share. DRAD has announced a plan to repurchase $2M of its stock, but it has not yet repurchased a material amount of stock.

The value proposition updated

Our updated estimate for the company’s liquidation value is set out below (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

drad-summary-2009-3-31

Balance sheet adjustments

We make the following adjustments to the balance sheet estimates above:

  • Cash burn: The company used $0.6M in cash in the first quarter. We have not included any cash burn in our estimate as DRAD’s first quarter’s cash burn was primarily due to a seasonal increase in DRAD’s inventory and a reduction in its accrued compensation and other liabilities and we do not expect this to be repeated in the second quarter.
  • Off-balance sheet arrangements and contractual obligations: The company hasn’t disclosed any off-balance sheet arrangements in its most recent 10K. The contractual obligations as at December 31 were around $3.0M, around $1.4M of which falls due in the next 12 months..

The catalyst

DRAD’s board has announced a stock buyback program:

The Company also announced that its board of directors has authorized a stock buyback program to repurchase up to an aggregate of $2 million of its issued and outstanding common shares. Digirad had approximately 19 million shares outstanding as of December 31, 2008. At current valuations, this repurchase plan would authorize the buyback of approximately 2.1 million shares, or approximately 11 percent of the company’s outstanding shares.

Chairman of the Digirad Board of Directors R. King Nelson said, “The board believes the Company’s direction and goals towards generating positive cash flow and earnings coupled with an undervalued stock price present a unique investment opportunity. We are confident this will provide a solid return to our shareholders.”

According to the most recent 10Q, the company has not bought back a material amount of stock:

On February 4, 2009, our board of directors authorized a stock buyback program to repurchase up to an aggregate of $2.0 million of our issued and outstanding common shares. The timing of stock repurchases and the number of shares of common stock to be repurchased are in compliance with Rule 10b-18 under the Securities Exchange Act of 1934. The timing and extent of the repurchase depends upon market conditions, applicable legal and contractual requirements, and other factors. During the three months ended March 31, 2009, we repurchased 11,000 shares of our common stock at a cost totaling $11,000.

Conclusion

At its $1.26 close yesterday, DRAD is trading at around 81% of its $29.5M or $1.56 per share in liquidation value. We see no reasons to cease holding DRAD in the Greenbackd Portfolio and so we’re going to maintain the position.

[Full Disclosure:  We do not have a holding in DRAD. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]
Read Full Post »

Long-term readers of Greenbackd might remember our initial struggle to apply the net net / liquidation formula described by Benjamin Graham in the 1934 Edition of Security Analysis in the context of modern accounting. Putting aside our attempt to include and tweak the discounts to PP&E (kind of like fixing the smile on the Mona Lisa), most embarassing was our failure to factor into the valuation off-balance sheet liabilities and contractual obligations. The best thing that we can say about the whole sorry episode is that we got there in the end and we’ve been applying a more robust formulation for the last quarter. With that in mind, we thought it was particularly interesting to see the Financial Post’s article, Veteran tweaks Graham’s rule to find bargains (via Graham and Doddsville), which details the refinements legendary value investor Marty Whitman makes to Graham’s net-net formulation.

According to the article, Whitman makes the following adjustments to Graham’s 90-year old formula:

  • Companies must be well-financed

First and foremost, companies must be well-financed in keeping with the core tenet of Third Avenue’s “safe and cheap” method of value investing.

The goal is to own companies that are going concerns, not ones destined for liquidation. This difference is a crucial point of distinction between the focus of equity investors, who are often wiped out in liquidation, and bond investors, who have rights to the assets of a company in liquidation.

  • Whitman includes long-term assets that are easily liquidated

The second adjustment is to the assets themselves. Graham and Dodd focused exclusively on current assets when calculating liquidation value whereas Whitman includes long-term assets that are easily liquidated.

For example, roughly one third of long-term assets of Toyota Industries Corp. are investment securities, including a 6% position in Toyota Motor Corp. (TM/TSX), says Ian Lapey, portfolio manager at Third Avenue and designated successor to Whitman on the Third Avenue Value Fund.

These securities are therefore included in Third Avenue’s calculations of net-net.

Closer to home, oil and gas producer Encana Corp. (ECA/ TSX) has proved reserves of oil and natural gas that are not included in current assets, says Lapey.

“They are liquid in that there is a real market, current commodity prices notwithstanding, for high-quality proved reserves of oil and gas.” Encana is a top holding in AIC Global Focused Fund, sub-advised by Third Avenue and managed by Lapey.

  • Adjust for off-balance sheet liabilities

The third adjustment is the inclusion of off-balance-sheet liabilities. Here, U. S. banks’ structured investment vehicles readily spring to mind.

  • Include some PP&E

The fourth and final adjustment to Graham and Dodd is the inclusion of “some property, plant and equipment” for their liquidated cash value and associated tax losses that often produce cash savings.

Hong Kong real estate companies, such as top holding Henderson Land Development Co. Ltd. (0012/HK),are required to mark property values to market prices, so liquidation values are easily ascertained.

“In most time periods, the market for fully leased office buildings is quite liquid,” says Lapey, justifying their inclusion in net-net calculations of these companies.

The article also discusses one of Whitman’s current positions, Sycamore Networks Inc (NASDAQ:SCMR):

Sycamore Networks Inc. (SCMR/NASDAQ) is the most compelling example of a net-net situation in the United States offered up by Lapey.

The telecom equipment company has more cash — US$935-million in all — than the total value assessed to it by the market, in light of its US$800-million market capitalization and US$38-million in total liabilities.

“We feel that there is value to their technology that is being recognized by some of the large telecom carriers,” says Lapey of Sycamore Networks, but he acknowledges its current weak earnings power. Lapey is also attracted to the one-third of outstanding share ownership by management because it presents an important alignment of their interests with those of Third Avenue, who are by and large passive investors.

These large valuation discounts in the market are reassuring words for investors from the one of the finest practitioners of Graham and Dodd.

“We are holding these companies trading at huge discounts,” says Lapey, “and if these companies were to sell assets or sell the whole companies we think the result would be a terrific return for our investment.”

As we discussed in our review of our first quarter, we started Greenbackd in an effort to extend our understanding of asset-based valuation described by Graham. Over the last few quarters we have refined our process a great deal, and it’s pleasing to us that we already include the adjustments identified by Whitman. We believe that our analyses are now qualitatively more robust than when we started out and seeing Whitman’s adjustments gives us some confidence that we’re on the right track.

Read Full Post »

Soapstone Networks Inc (NASDAQ:SOAP) has filed its 10Q for the quarter ended March 31, 2009.

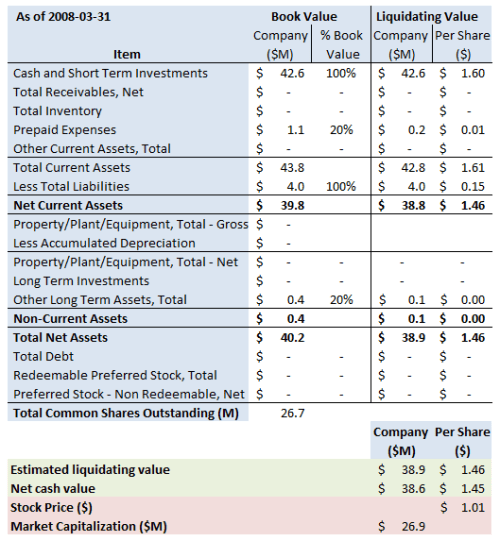
We been following SOAP (see our post archive here) because it is trading well below its net cash value with an activist investor, Mithras Capital, disclosing an 8.7% holding in October last year. The stock is up 48.0% from $2.50 when we initiated our position to close yesterday at $3.70, giving SOAP a market capitalization of $52.0M. We last estimated the company’s net cash value to be $86.1M or $5.59 per share. Following our review of the Q1 10Q, we’ve adjusted our valuation down 6% to $80.3M or $5.21 per share as a result of $6.7M of cash burned.

The value proposition updated

The company’s balance sheet value is almost wholly cash, which it continues to burn (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

soap-summary-2009-3-311

Balance sheet adjustments

We need to make the following adjustments to the balance sheet estimates above:

  • Cash burn: The company used $6.7M in cash in the first quarter. They expect cash burn to continue to be between $6M and $6.5M per quarter.
  • Off-balance sheet arrangements and contractual obligations: SOAP does not have any off-balance-sheet arrangements and its contractual obligations, which consist entirely of operating leases, are $3.9M. These operating lease payments are the minimum rent expense for SOAP’s facilities, including its head office.

Conclusion

We continue to believe that SOAP is a very good opportunity. The company’s ongoing business is small in comparison to its net cash position, so it shouldn’t dissipate its cash any time soon. It has no off-balance sheet arrangements, little in the way of ongoing contractual obligations and no material litigation, so the cash position seems reasonably certain. The company’s engagement of an investment bank to explore strategic alternatives is a promising step in the right direction. We continue to be concerned by the continued issuance of options at a huge discount to liquidation value. The sooner Mithras Capital gets control of this situation the better.

[Full Disclosure:  We have a holding in SOAP. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]
Read Full Post »

Vanda Pharmaceuticals Inc. (NASDAQ:VNDA) has reported its results for the first quarter ended March 31, 2009.

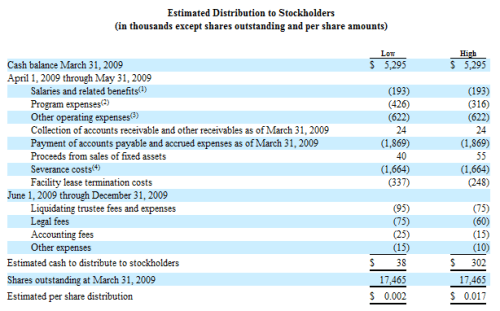
We’ve been following VNDA (see our post archive here) because it’s trading below its net cash value and Tang Capital Partners (TCP) has called for the company to “cease operations immediately, liquidate [VNDA]’s assets and distribute all remaining capital to the Stockholders.” TCP has now filed a preliminary proxy statement for the 2009 Annual Meeting urging stockholders to support TCP’s slate of two director nominees, Kevin C. Tang and Andrew D. Levin, M.D., Ph.D. The stock is up 29.5% since we initiated the position to close yesterday at $1.01, giving the company a market capitalization of $24.3M. We initially estimated the net cash value to be around $42.6M or $1.60 per share. We’ve now reduced our estimate of the net cash value to $38.6M or $1.45 per share. The company continues to hemorrhage cash, so the investment turns on TCP’s ability to get control of the board at the Annual Meeting and staunch the bleeding. If TCP cannot get onto the board quickly, the company will continue to burn cash and the investment will be a dud. VNDA has a staggered board, which makes TCP’s task difficult.

The value proposition updated

In the first quarter of 2009 VNDA burned through $3.8M in cash, which reduces our estimate of the net cash value from $42.6M to $38.6M or $1.45 per share (the remaining difference is due to the slight increase in shares on issue). Set out below is our summary balance sheet  (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

vnda-summary-2009-12-31

Conclusion

VNDA continues to be an interesting play. While the stock is up nearly 30% since we initiated the position, it is still trading at a 45% discount to our estimate of its $1.45 per share net cash value. That value is of course deteriorating rapidly, and the challenge for investors is to determine which of two outcomes is more likely: If TCP can get on the board quickly, stop the cash burn and liquidate the company, we’re likely to see a good return. If TCP cannot get onto the board quickly or at all, the company will continue to burn cash and the investment will be a dud. VNDA has a staggered board, so this will make TCP’s task difficult. We’re inclined to maintain our position and see how this plays out.

[Full Disclosure:  We do not have a holding in VNDA. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Genaera Corporation (NASDAQ:GENR) is a first for us: a short play. The company has announced that the board of directors has approved a Plan of Liquidation and Dissolution forecasting distributions of between $0.002 and $0.0173 per share contingent on a sale of its assets. We believe the most likely outcome to be a distribution of nil. The stock is currently at $0.18. The risk to the short position is a sale of the company’s intellectual property, which we think is unlikely for the reasons we describe below.

About GENR

GENR is a biopharmaceutical company focused on advancing the science and treatment of metabolic diseases. It has announced a plan to liquidate:

Genaera Corporation Announces Approval of Plan of Liquidation and Dissolution by Board of Directors

Plymouth Meeting, PA – April 28, 2009 – Genaera Corporation (the “Company”)(NASDAQ: GENR) today announced that its Board of Directors has determined, after extensive and careful consideration of the Company’s strategic alternatives, that it is in the best interests of the Company and its stockholders to liquidate the Company’s assets and to dissolve the Company. The Company’s Board of Directors has approved a Plan of Complete Liquidation and Dissolution of the Company (the “Plan of Dissolution”), subject to stockholder approval. The Company intends to hold a special meeting of stockholders to seek approval of the Plan of Dissolution and has filed preliminary proxy materials with the Securities and Exchange Commission (“SEC”) and will file definitive proxy materials in the near future.

The Plan of Dissolution contemplates an orderly wind down of the Company’s business and operations. If the Company’s stockholders approve the Plan of Dissolution, the Company intends to file articles of dissolution, satisfy or resolve its remaining liabilities and obligations, including but not limited to contingent liabilities and claims, lease obligations, severance for terminated employees and costs associated with the liquidation and dissolution, and attempt to convert all of its remaining assets into cash or cash equivalents. Based on current projections of operating expenses and liquidation costs the Company currently estimates that it will not make liquidating distributions to stockholders unless and until a sale of one or all of its assets has been consummated. Following stockholder approval of the Plan of Dissolution and the filing of articles of dissolution, the Company would delist its common stock from NASDAQ.

If, prior to its dissolution, the Company receives an offer for a corporate transaction that will, in the view of the Board of Directors, provide superior value to stockholders than the value of the estimated distributions under the Plan of Dissolution, taking into account all factors that could affect valuation, including timing and certainty of closing, credit market risks, proposed terms and other factors, the Plan of Dissolution could be abandoned in favor of such a transaction.

The value proposition

GENR has funded its operations primarily from the proceeds of public and private placements of its securities and through contract and grant revenues, research and development expense reimbursements, the sale of a Pennsylvania research and development tax credit carry forwards and interest income. It has not nor will it ever have products available for sale and has incurred losses since inception.

The notice of special meeting filed yesterday anticipates a maximum distribution of $0.0173 per share and the company does not expect to make a distribution “unless and until a sale of one or all of our assets has been consummated.” The balance sheet as at March 31, 2009 shows $5.3M in cash and equivalents less $2M in liabilities, which equates to a net cash value of $3.3M or $0.19 per share before we deduct the following:

  • ongoing operating expenses;
  • expenses incurred in connection with extending directors’and officers’ insurance coverage;
  • expenses incurred in connection with the liquidation and dissolution process;
  • severance and related costs; and
  • professional, legal, consulting and accounting fees.

Assuming between $3M and $4M for the foregoing, GENR has between $0.02 per share and nil net cash value in liquidation, with nil being more likely.

The company’s own estimates are as follows:

Based on our current projections of operating expenses and liquidation costs, we currently estimate that distributions to stockholders would only occur in the event of a consummation of the sale of one or more of our assets:

genr-summary

(1) Estimated salaries and related benefits for employees through May 31, 2009.
(2) Represents final research and development expenses related to the wind down of our trodusquemine program, including clinical trial costs, third-party contract research costs and manufacturing expenses.
(3) Other operating expenses consists of facilities expenses, legal, accounting and intellectual property expenses, consulting and other fees and insurance costs including the payment of $255,000 for directors and officers liability insurance covering six years from the date of stockholder approval of the Plan of Dissolution.
(4) Estimated cash use for severance payments to employees remaining after March 31, 2009, including Executive Officers. Amounts included in the table for Executive Officers do not include amounts due under the Executive Officers and Dr. Wolfe’s change of control agreements. See “Interests of Certain Directors and Executive Officers in Approval of the Plan of Dissolution – Summary of Benefits of Certain Executive Officers” for additional information related to severance payments to the Executive Officers. The severance costs shown in the table include $1,012,000 to be paid to the Executive Officers, $516,000 to be paid to other employees, $95,000 of associated payroll taxes and $42,000 for ongoing health benefits under employee severance agreements for all employees.

The risk to this analysis is the company actually manages to sell its intellectual property assets, and we’re going to explore GENR’s efforts to sell those assets in some detail below.

Likelihood of asset sales

According to the proxy statement for the special meeting, GENR has made extensive efforts to sell or license its intellectual property without success since 2008. Throughout 2008 management contacted over 90 prospective strategic partners, both domestic and international. This resulted in approximately 25 companies signing non-disclosure agreements and receiving non-public evaluation materials. Subsequently, two parties submitted expressions of interest in the purchase of two separate assets.

GENR and its legal advisors have been engaged in discussions with one prospective purchaser in an attempt to reach an agreement regarding the acquisition price and the other terms of a definitive agreement. According to GENR, the parties are generally in agreement on the proposed terms of a definitive agreement and continue to communicate, but have been unable to complete the transaction. With regard to the second potential purchaser, GENR is currently engaged in discussions in an attempt to reach an agreement regarding the acquisition price of the other asset.

In 2009, as a result of limited interest in GENR’s other assets and the unanticipated delay in the consummation of the transaction, GENR engaged of outside parties to assist in licensing and/or partnering its trodusquemine program. The scope of the oustide engagement included searching for a purchaser, licensee or partner acceptable to GENR and assisting it in negotiating the financial aspects of a transaction.

Between January and March 2009, the oustide parties contacted 43 potential purchasers and/or partners, which resulted in 23 rejections, 9 pending reviews and the execution of 11 non-disclosure agreements to review non-public evaluation materials. The review of confidential information resulted in six rejections and meaningful discussions with three potential licensors and/or purchasers.

At the April 8, 2009 meeting of the board, the board reviewed the prospects for partnering and/or licensing the trodusquemine program, the status of the sales of two of its assets, as well as alternative means to fund the company. As neither of the asset sales had been consummated or were projected to be consummated imminently, the board instructed management to prepare a plan of dissolution in conjunction with the outside counsel for review and consideration at the next board meeting.

Conclusion

GENR is a short play because the current stock price is almost ten times the company’s projected distribution in the liquidation of the company. The stock is currently at $0.18. The company forecasts distributions of between $0.002 and $0.0173 per share contingent on a sale of its assets. We believe there is a very real possibility the distribution could be nil.  The risk to the short position is a sale of the company’s intellectual property, which we think is unlikely.

Hat tip Anon.

Read Full Post »

Autobytel Inc’s (NASDAQ:ABTL) board has responded to Trilogy, Inc’s $0.35 per share tender offer, calling it “grossly inadequate” and “unequivocally” recommending that stockholders reject it.

We started following ABTL (see our post archive here) because it was trading at a substantial discount to its liquidation and net cash values and Trilogy had filed a 13D notice disclosing a 7.4% holding. Trilogy has now launched a tender offer for ABTL at $0.35 per share, which is at our estimate of ABTL’s $15.4M or $0.34 per share net cash value, but at a substantial discount to our estimate of ABTL’s $24.3M or $0.54 per share liquidation value. When Trilogy launched its offer, we wrote that we believed that $0.35 per share was only the opening salvo and a higher price was possible if the board terminated the rights plan poison pill. The stock closed yesterday at $0.515, which is a huge 47% premium to Trilogy’s offer price and suggests the market is also anticipating a higher offer. The stock is up 19.8% since we started following it in December.

Here’s the letter from ABTL:

April 27, 2009

Dear Stockholder:

On Monday, April 20, 2009, I received a letter from Trilogy Enterprises, Inc. (“Trilogy”) indicating that Trilogy had launched a tender offer for all of Autobytel Inc.’s (our “Company”) outstanding shares of common stock at $0.35 per share.

Our Board of Directors (our “Board”), in consultation with its legal and financial advisors, has evaluated Trilogy’s offer and has found Trilogy’s $0.35 offer price to be grossly inadequate and unequivocally recommends to stockholders that they reject Trilogy’s offer and not tender their shares to Trilogy.

Our Board also believes that the combination of actions taken by our Company as described below will result in our stockholders achieving significantly more value than the offer made by Trilogy. In reaching its decision to recommend that stockholders reject the Trilogy offer and not tender their shares to Trilogy, our Board considered many factors, including:

• Our Company’s strong balance sheet and current cash and receivables position, noting, in particular, that our Company’s cash position alone is substantially in excess of Trilogy’s offer.

• The initial reaction of the securities trading markets to Trilogy’s offer appears to support our Board’s decision that the offer price is inadequate.

• The recent thorough evaluation of strategic alternatives conducted by our Board, including the possible sale of our Company, which concluded that selling our Company in today’s environment was not in the best interest of maximizing value.

• The indications of interest received and offers from potential buyers for our Company as a result of the sale process.

• Inquiries made to our Company’s financial advisor by other interested parties in response to Trilogy’s offer.

• The reasons for the Board’s decision to terminate the sale process, including:

• The value of our Company’s websites; and

• The value of our Company’s intellectual property, particularly its patents, which resulted in a $20 million settlement with the Dealix Corporation in 2006 and most recently settlements with Edmunds.com, Internet Brands, InsWeb and Lead Point that will provide our Company with valuable content, images, shopping and interactive tools and data for our websites.

• Other strategic alternatives being evaluated by our Board and management team.

• The belief that Trilogy is being opportunist in exploiting a recent extreme price decline in our common stock and use of confidential information about our Company obtained by Trilogy under a non-disclosure agreement.

Based upon the above, our Board recommends that you reject Trilogy’s offer and not tender your shares of common stock for purchase by Trilogy.

In addition, we encourage you to read the enclosed Schedule 14D-9, which provides further details with regard to our Board’s recommendation and discusses the factors that our Board carefully considered and evaluated in making its decision to reject Trilogy’s offer.

If you have any questions, please do not hesitate to contact our information agent, MacKenzie Partners, Inc., at the following numbers: Toll-Free 1-800-322-2885 or at 1-212-929-5500 (collect) or by email at autobytel@mackenziepartners.com.

On Behalf of the Board of Directors,

Jeffrey H. Coats
President and Chief Executive Officer

At $0.515, ABTL has a market capitalization of $23.3M, which is approaching our estimate of its $0.54 per share liquidation value. We’re planning to maintain the position as we believe a higher bid is on the cards and Trilogy will know that it is unlikely to get sufficient acceptances at a discount to ABTL’s liquidation value.

[Full Disclosure:  We do not have a holding in ABTL. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]
Read Full Post »

Ikanos Communications Inc (NASDAQ:IKAN) has acquired the assets of the Broadband Access product line from Conexant Systems, Inc. (NASDAQ: CNXT) for $54M partially funded by a sale of $42M in common stock at $1.75 per share to Tallwood Venture Capital. Upon completion of the transaction, Tallwood Venture Capital will own approximately 45% of IKAN, which means that the possibility of any catalytic event occurring is now remote. While IKAN is still trading at a discount to our calculation of its liquidation and net cash values, without a catalyst our investment thesis is gone, so we’re exiting the position.

We opened the IKAN position at $1.14 and it closed Friday at $1.37, which means we’re up 20.2% on an absolute basis. The S&P500 Index was at 836.57 when we opened the position and closed yesterday at 866.23, which means we’re up 16.6% on a relative basis.

Post mortem

We started following IKAN (see our post archive here) because it was trading at a discount to its net cash and had retained a financial adviser to “assist it in exploring and evaluating strategic alternatives to maximize shareholder value.” IKAN disclosed in its September 10Q that it had retained investment bankers to advise the board about IKAN’s strategic options:

We recently decided to retain Barclays Capital (formerly Lehman Brothers) to provide financial advice regarding potential strategic options for the Company. Such options include, without limitation, financing transactions, acquisitions, strategic partnerships, corporate restructuring and other activities. There can be no assurance that the evaluation of our options will result in the identification, announcement or consummation of any transaction. If the Board of Directors does decide to authorize a transaction, that decision could cause significant volatility in the price of the Company’s outstanding common stock. Moreover, any transactions we do sign may not be acceptable to our stockholders. In addition, our investigation of strategic options may result in added costs, potential loss of customers and key employees as well as management’s distraction from ordinary-course business operations.

We said at the time that there seemed to be some appetite for acquisitions in this industry giving the example of IKAN’s competitor Centillium Communications Inc (NASDAQ: CTLM), which was acquired in October last year. We were hoping that IKAN was to be the vendor, but it seems the “strategic option” favored by IKAN and its investment bankers is to be the acquisition of Conexant’s Broadband Access product line. Here’s the press release:

Ikanos Communications Announces Plans to Acquire Conexant’s Broadband Access Product Line

Tallwood Venture Capital Invests $42 Million

Webcast and Conference Call Details Included for this Event and for

First Quarter 2009 Financial Results

FREMONT, Calif., April 22, 2009, Ikanos Communications, Inc. (NASDAQ: IKAN), a leading provider of broadband semiconductor and software products for the digital home, today announced the signing of a definitive agreement to purchase the Broadband Access product line from Conexant Systems, Inc. (NASDAQ: CNXT). The combined organization will have the expertise and resources required to satisfy the demand for powerful broadband network products around the world.

Under the terms of the agreement, which was unanimously approved by the boards of directors of both companies, Ikanos will purchase Conexant’s Broadband Access product line for $54 million in cash and the assumption of certain employee and facility related liabilities. In connection with this transaction, Tallwood Venture Capital, a leading investment firm focused on the semiconductor industry, has agreed to purchase 24 million shares of Ikanos common stock for $42 million, or $1.75 per share. Tallwood will also receive warrants to purchase an additional 7.8 million shares of common stock at $1.75 per share. The warrants will have a term of five years. Upon completion of the transactions, Tallwood Venture Capital will own approximately 45 percent of the outstanding shares of Ikanos (excluding the warrants). In addition, following the transaction, George Pavlov, general partner, and Dado Banatao, managing partner, will join Ikanos’ Board of Directors.

Ikanos’ purchase of Conexant’s Broadband Access product line is subject to customary closing conditions, including stockholder and regulatory approvals, and is expected to be completed in the third quarter of calendar year 2009.

Ikanos expects that the transaction will more than double the Company’s revenue, while providing significant leverage in its cost and spending structure. Ikanos also expects that the transaction will be accretive to its non-GAAP earnings per share within the first year after the close of the transaction.

“With the number of home networks doubling to more than 400 million by 2013 according to analysts, there’s a substantial opportunity for Ikanos to address the need for delivering bandwidth to and throughout the home,” said Michael Gulett, president and CEO of Ikanos. “We’ll use our strengthened leadership in broadband access as a platform on which to build new offerings that extend multi-play services seamlessly everywhere they are needed.”

Today, Ikanos and Conexant account for a cumulative 330 million broadband access ports shipped, bringing the power of the Internet to millions of people around the world. Conexant’s Broadband Access product line has traditionally been strong in North America and China while Ikanos has led in Japan, Korea and Europe. The combined company will be well positioned to address the global market for broadband semiconductors, and better serve customers in all geographies.

“Customers should not be concerned about product transitions. Once the acquisition is complete, the combined company will continue to make available and support the products acquired from Conexant along with the products of Ikanos,” added Gulett.

The combination of Ikanos and Conexant’s Broadband Access product line brings together the industry’s most comprehensive portfolio of broadband access products. Ikanos will build on its status as the VDSL market share leader, will add substantial ADSL market share, and will have a broad product portfolio that includes SHDSL, 802.11 b/g wireless networking, Ethernet switching, and passive optical networking (PON). In addition, the combined company will have both MIPS- and ARM-based processors that are powering broadband access networks around the world.

The combined company will also have the expertise to enable service providers and network equipment manufacturers to effectively build advanced networks, and deploy multi-play services including high-speed Internet, Internet protocol television (IPTV), voice-over Internet protocol (VoIP) and fixed-mobile convergence (FMC) offerings. The combined organization’s customers will include a vast array of industry leading network equipment manufacturers and service providers from around the world.

“The combined company brings together a talented team of employees that pioneered and set the standards for the broadband market,” said Craig Garen, senior vice president and general manager of Conexant’s Broadband Access business. “Going forward, we’ll continue to innovate and create new broadband access and home networking products that deliver enhanced value to the marketplace.”

Both Ikanos and Conexant have been strong, active proponents of industry standards, and are advancing the development of next-generation technologies like ITU-T G.hn for whole-home networking, retransmission and the dynamic spectrum management. The combined company will have a portfolio of intellectual property that will include well over 400 patents and applications.

“This transaction brings together a powerful combination of leading products, strong customer relationships, and deep technical expertise, all dedicated to the broadband market,” said George Pavlov, general partner at Tallwood Venture Capital. “The new company that emerges will be able to compete more effectively in existing and emerging markets, develop exciting new products, and provide greater value for its most important stakeholders – its customers, investors and employees.”

IKAN is still trading at a discount to both its net cash and liquidation valuations, so it’s difficult to exit when the possibility of additional upside is good. IKAN is still burning cash, so that value will deteriorate, and our investment thesis was based on some catalytic event occurring before the value was dissipated. Tallwood Venture Capital’s 45% holding (excluding the 7.8M warrants) means that Tallwood has control, which in turn means the chance of a catalytic event occurring that could realize that value is now low. For those reasons, we’re out.

Hat tip to JM.

[Full Disclosure:  We have a holding in IKAN. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Empirical Finance Research Blog has a review of a new paper, Hedge Fund Activism, Corporate Governance, and Firm Performance, which finds that the “market reacts favorably to hedge fund activism, as the abnormal return upon announcement of potential activism is in the range of seven percent, with no return reversal during the subsequent year.” Further, the paper “provides important new evidence on the mechanisms and effects of informed shareholder monitoring.”

The authors seek to address the questions posed by “critics and regulators” about the benefits of hedge fund activism to shareholders and the claim that hedge fund activists “destroy value by distracting managers from long-term projects.” Specifically, the paper seeks to answer the following questions:

  • Which firms do activists target and how do those targets respond?
  • How does the market react to the announcement of activism?
  • Do activists succeed in implementing their objectives?
  • Are activists short-term in focus?

We’ve set out below brief answers to the questions posed in the paper:

Which firms do activists target and how do those targets respond?

Hedge fund activists tend to target companies that are typically “value” firms, with low market value relative to book value, although they are profitable with sound operating cash flows and return on assets. Payout at these companies before intervention is lower than that of a matched sample. Target companies also have more takeover defenses and pay their CEOs more than comparable companies. Relatively few targeted companies are large-cap firms, which is not surprising given the relatively high cost of amassing a meaningful stake in such a target. Targets exhibit significantly higher institutional ownership and trading liquidity. These characteristics make it easier for activists to acquire a significant stake quickly.

How does the market react to the announcement of activism?

We find that the market reacts favorably to activism, consistent with the view that it creates value. The filing of a Schedule 13D revealing an activist fund’s investment in a target firm results in large positive average abnormal returns, in the range of 7 to 8 percent, during the (-20,+20) announcement window. The increase in both price and abnormal trading volume of target shares begins one to ten days prior to filing. We find that the positive returns at announcement are not reversed over time, as there is no evidence of a negative abnormal drift during the one-year period subsequent to the announcement. We also document that the positive abnormal returns are only marginally lower for hedge funds that disclosed substantial ownership positions (through quarterly Form 13F filings) before they file a Schedule 13D, which is consistent with the view that the abnormal returns are due to new information about activism, not merely that about stock picking. Moreover, target prices decline upon the exit of a hedge fund only after it has been unsuccessful, which indicates that the information reflected in the positive announcement returns conveys the market’s expectation for the success of activism.

Activism that targets the sale of the company or changes in business strategy, such as refocusing and spinning-off non-core assets, is associated with the largest positive abnormal partial effects of 8.54 percent and 5.95 percent, respectively (the latter figure is lower than the overall sample average because most events target multiple issues). This evidence suggests that hedge funds are able to create value when they see large allocative inefficiencies. In contrast, we find that the market response to capital-structure related activism – including debt restructuring, recapitalization, dividends, and share repurchases – is positive, yet insignificant. We find a similar lack of statistically meaningful reaction for governance-related activism-including attempts to rescind take-over defenses, to oust CEOs, to enhance board independence, and to curtail CEO compensation. Hedge funds with a track record of successful activism generate higher returns, as do hedge funds that initiate activism with hostile tactics.

Do activists succeed in implementing their objectives?

The positive market reaction is also consistent with ex-post evidence of overall improved performance at target firms. On average, from the year before announcement to the year after, total payout increases by 0.3-0.5 percentage points (as a percentage of the market value of equity, relative to an all-sample mean of 2.2 percentage points), and book value leverage increases by 1.3-1.4 percentage points (relative to an all-sample mean of 33.5 percentage points). Both changes are consistent with a reduction of agency problems associated with free cash flow and subject managers to increased market discipline.

We also find improvement in return on assets and operating profit margins, but this takes longer to happen. The post-event year sees little change compared to the year prior to intervention. However, EBITDA/Assets (EBITDA/Sales) at target firms increase by 0.9-1.5 (4.7-5.8) percentage points by two years after intervention. Analyst expectations also suggest improved prospects at target firms after hedge fund intervention. During the months before Schedule 13D filings, analysts downgrade (future) targets more than they upgrade them whereas after intervention is announced analysts maintain neutral ratings. Given that successful activism often leads to attrition through sale of the target company, ex post performance analysis based on surviving firms may underestimate the positive effect of activism.

Are activists short-term in focus?

Hedge fund activists are not short-term in focus, as some critics have claimed. The median holding period for completed deals is about one year, calculated as running from the date a hedge fund files a Schedule 13D to the date when the fund no longer holds a significant stake in a target company. The calculation substantially understates the actual median holding period, because it necessarily excludes events where no exit information is available by March 2007. Analysis of portfolio turnover rates of the funds in our sample suggests holding periods of closer to twenty months.

Empirical Finance Research has some tips for implementing the “hedge fund activist alpha strategy” based on their experience watching real-world activists work their magic:

1. Focus on small companies

2. Watch for activists who are entering companies at the same time mutual funds are dumping (watch for 13-G’s filed concurrently with 13Ds). This way you can buy at cheap prices while the mutual funds are putting pressure on the stock. Eventually, the selling pressure is gone AND you have an activist there to make sure the ship is sailing straight ahead.

3. Call the company in question and assess how ‘open’ they are. Sometimes even the best activist campaign can’t beat an overly entrenched and crooked management.

4. Call the activist and get a feel for what they want to do with the company. In my experience, activist investors are usually class-act capitalists and may give you hints as to the direction they want to take a company.

5. Do your own due diligence and determine where the ‘hidden’ value is located. If you have an assessment of exactly what the activist is after, you may be able to determine how successful they will be in their attempts to unlock this value. Here is a quick example. If you determine the activist wants to unlock value when there is a discrepancy between the value of an asset on the books and the value of an asset in the real-world (i.e. a real estate holding), but you determine that selling the asset would be a nightmare (maybe you live down the street from the property) and/or involves abusive tax treatment that not many people understand, you may shy away from following the activist.

Read Full Post »

In Ackman and Target Tangle in Ballot Brawl, The New York Times’ Dealbook has coverage of the “universal ballot” spat between William A. Ackman’s Pershing Square Capital and Target Corporation (NYSE:TGT).  A candidate on Pershing Square’s ticket, Ronald J. Gilson, who is a law professor at Stanford University and an expert in corporate governance, has proposed that TGT place all the nominees running for election to the board on a single ballot, the so-called “universal ballot.” Presently, shareholders in most proxy fights receive two proxy cards and can vote only for one slate of candidates. Gilson’s proposal would give TGT’s shareholders the chance to pick candidates from both management and Pershing Square’s proxies.

Dealbook reports that the shareholder advisory firm RickMetrics Group support the universal ballot proposal:

“Pershing appears to be astutely exploiting the current pro-(shareholder)-choice zeitgeist, and puts Target on its back foot,” RiskMetrics said in a research note issued Tuesday. “It will be challenging for Target, absent some sort of unwaivable legal impediment, to argue against Pershing’s proposal without coming across as anti-shareholder.”

Here is Gilson’s letter to the board:

RONALD J. GILSON

Charles J. Meyers Professor
of Law and Business

April 21, 2009

Mr. Gregg Steinhafel
Chairman of the Board
Chief Executive Officer and President
Mr. Timothy R. Baer
Executive Vice President
Corporate Secretary and General Counsel
Target Corporation
1000 Nicollet Mall
Minneapolis, Minnesota 55403

Re: Proposal to Use a Universal Proxy at the2009 Annual Meeting of Shareholders

Dear Messrs. Steinhafel and Baer:

On March 17, 2009, Pershing Square Capital Management, L.P. publicly announced that its affiliates had delivered a Notice of Nomination to you proposing to nominate five individuals for election as directors of Target at the company’s 2009 Annual Meeting of Shareholders. I am one of those nominees.

Both Target and Pershing Square have a unique opportunity to make this election historic from a corporate governance perspective. As you may know, the press has reported that SEC chair Mary Schapiro has directed the Commission’s staff to draft proposals for rules governing shareholder proxy access by mid-May 2009. I expect those proposed rules will provide the opportunity for the use of a universal proxy card whereby shareholders can choose – on one proxy card – from among the candidates nominated both by the company and by shareholders. The benefit to shareholders, who may want to choose members from both slates, would be substantial.

I first wrote about the need to remove the barriers to non-control proxy contests some 19 years ago.1 The occasion then was to recommend a change in the bona fide nominee rule to allow a shareholder running a short slate to include the names of the company’s nominees on the shareholder’s proxy card. That recommendation was accepted by the SEC, as I recall at the urging of Mary Schapiro, who was then a Commissioner.

Target and Pershing Square now have the opportunity to proactively provide good corporate governance to the Target shareholders by making it convenient for them to make a choice in what, in the end, is their election. This is not a control contest. The qualifications of the candidates will be fully vetted by the time of the May 28th election, and Target shareholders are entirely capable of assessing the candidates and making a choice. There is simply no excuse to deny shareholders the benefit of the use of a universal proxy card. The alternative will make it procedurally more difficult for Target shareholders to exercise their franchise. This is a problem that we, together, have the power to solve.

I have received assurance from Pershing Square that they would support a universal proxy card for Target’s upcoming Annual Meeting. I now seek the same from you. In the alterative, I ask that you consider allowing the company’s nominees to be named on the Pershing Square Gold proxy card. In either instance, shareholders would have the benefit of being able to choose the best nominees for the job. Target now has the opportunity to hold an election that will be a credit to the company’s corporate governance. I urge you to carefully consider this proposal and do the right thing for Target shareholders.

Very truly yours,

/s/ Ronald J. Gilson

1 Ronald J. Gilson, Lilli A. Gordon & John Pound, How the Proxy Rules Discourage Constructive Engagement: Regulatory Barriers to Electing a Minority of Directors, 17 Journal of Corporate Law 29 (with L. Gordon & J. Pound) (1992).

Here is TGT’s response:

TARGET CORPORATION COMMENTS ON LETTER FROM PERSHING SQUARE NOMINEE RONALD GILSON

MINNEAPOLIS, April 21, 2009 – Target Corporation (NYSE:TGT) today commented on the letter from Pershing Square nominee, Professor Ronald J. Gilson, that Pershing Square filed with the Securities and Exchange Commission (“SEC”). In the letter, Professor Gilson references possible future SEC changes to the federal proxy rules and proposes the use of a universal proxy card by Target and Pershing Square. Pershing Square has initiated a proxy contest to elect its own nominees, including Professor Gilson, to Target’s Board of Directors.

The company said, “We believe Professor Gilson’s proposal, coming at this stage of the proxy contest, would cause delay and confusion. Shareholders have a clear choice between our independent nominees on our WHITE proxy card and Bill Ackman’s slate on Pershing Square’s gold proxy card. We note, as does Professor Gilson, that the SEC may be considering a proxy access proposal. Any such proposal should be allowed to proceed on an appropriate timetable allowing for careful review and consideration by the SEC of a number of issues, including whether proxy access should be available to an entity, like Pershing Square, which has initiated its own proxy contest. In the meantime, the current proxy rules provide a framework for the conduct of the proxy voting process that is perfectly adequate for resolving the issues that Pershing Square is raising.

“With Target’s Annual Meeting only five weeks away, we believe our shareholders clearly understand the choice between our independent directors and the Pershing Square slate. We will be mailing our proxy materials shortly and encourage our shareholders to use our WHITE proxy card to support the reelection of the directors nominated by our Board.”

Shareholders who have questions about voting or the matters to be voted upon at the Annual Meeting are encouraged to call MacKenzie Partners, Inc. at 800-322-2885 Toll-Free or Georgeson at 866-295-8105 Toll-Free. The company will hold the 2009 Annual Meeting of Shareholders on Thursday, May 28, 2009. Target will be distributing proxy materials to shareholders of record as of March 30, 2009.

And Pershing Square’s response:

Pershing Square Comments on
Target’s Objection to Universal Ballot Proposal

New York – Pershing Square Capital Management, L.P., and Professor Ronald J. Gilson, who has been nominated by Pershing Square to serve as an independent director of Target Corporation (NYSE: TGT), expressed disappointment with Target’s response to Professor Gilson’s letter seeking the use of a universal proxy card, naming both Target’s and Pershing Square’s nominees, for use in connection with Target’s upcoming Annual Meeting of Shareholders.

“Rather than causing confusion, the proposal would eliminate confusion by giving shareholders something they would otherwise lack – the simple chance to choose the best among all of the candidates, rather than between two slates of candidates.” commented Professor Gilson. Pershing Square believes that the adoption by both Target and Pershing Square of a universal proxy card would reflect best-in-class corporate governance, and would result in the most qualified directors being elected, regardless of which proxy card a shareholder returned.

On the universal proxy card proposal, Bill Ackman of Pershing Square said, “it’s important for shareholders to have a choice so that they can vote for whichever candidates they prefer, regardless of which proxy card they submit. Pershing Square wants to provide shareholders with that freedom of choice. We are hoping Target will as well.”

Because proxy cards have not yet been mailed, and because new proxy cards are easy to print from the company’s or Pershing Square’s website, Pershing Square does not believe that adopting a universal proxy card would add any material expense to the proxy contest. Pershing Square also noted that it would be willing to bear the additional printing costs of the universal proxy cards.

Furthermore, Target’s public explanation for its refusal to use a universal proxy card does not address why Target would not permit its nominees to be named on Pershing Square’s Gold proxy card. Indeed, based on the timing of Target’s public response, Pershing Square questions how the matter could have been raised with its Board of Directors and whether Target’s nominees were given the opportunity to consent to being named on a universal proxy card or Pershing Square’s Gold proxy card.

Pershing Square requests Target’s nominees for permission to be included on the Gold proxy card in the event that the company will not consent to a universal proxy card.

[Full Disclosure:  We do not have a holding in TGT. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

« Newer Posts - Older Posts »