Feeds:
Posts
Comments

Archive for the ‘Stocks’ Category

Northstar Neuroscience Inc (NASDAQ:NSTR) has filed its notice of special meeting of shareholders annexing the Plan of Complete Liquidation and Dissolution (Plan).

We started following NSTR because it is a net cash stock that has announced that it plans to liquidate. NSTR closed yesterday at $1.85, giving it a market capitalization of $48.4M. We originally estimated the final pay out figure in the liquidation to be around $59M or $2.26 per share, which presents an upside of around 25%. The company estimates a slightly lower pay out figure of between $1.90 and $2.10 “assuming we are unable to sell our non-cash assets” and expects to make an initial distribution within approximately 45 days after the Effective Date (which is to be announced) of approximately $1.80 per share. The following is extracted from the Plan:

Q: What will shareholders receive in the liquidation?

A: Pursuant to the Plan of Dissolution, we intend to liquidate all of our remaining non-cash assets and, after satisfying or making reasonable provision for the satisfaction of claims, obligations and liabilities as required by law, distribute any remaining cash to our shareholders. We can only estimate the amount of cash that may be available for distribution among our shareholders. We currently estimate that the amount ultimately distributed will be between approximately $1.90 and $2.10 per share of common stock, assuming we are unable to sell our non-cash assets. Many of the factors influencing the amount of cash distributed to our shareholders as a liquidating distribution cannot be currently quantified with certainty and are subject to change. Accordingly, you will not know the exact amount of any liquidating distributions you may receive as a result of the Plan of Dissolution when you vote on the proposal to approve the Plan of Dissolution. You may receive substantially less than the amount we currently estimate. See “Proposal 1: Approval of Plan of Dissolution-Estimated Liquidating Distributions.”

Q: When will shareholders receive payment of any available liquidation proceeds?

A: Although we are not able to predict with certainty the precise nature, amount or timing of any distributions, we presently expect to make an initial distribution, within approximately 45 days after the Effective Date, to holders of record of our common stock as of the close of business on the Effective Date of approximately $1.80 per share. We do not intend to make any further distributions until after we sell, liquidate or otherwise dispose of our remaining non-cash assets, consisting primarily of our RenovaTM Cortical Stimulation System and related intellectual property, and pay or otherwise make reasonable provision for the payment of claims against and obligations of Northstar. We are not able to predict with certainty the precise nature, amount or timing of any distributions, primarily due to our inability to predict the amount of our remaining liabilities or the amount that we will expend during the course of the liquidation and the net value, if any, of our remaining non-cash assets. To the extent that the amount of our liabilities or the amounts that we expend during the liquidation are greater, or the value of our non-cash assets is less, than we anticipate, our shareholders may receive substantially less than the amount we currently estimate. Our board of directors has not established a firm timetable for any final distributions to our shareholders. Subject to contingencies inherent in winding up our business, our board of directors intends to authorize any distributions as promptly as reasonably practicable in the best interests of Northstar and its shareholders. Our board of directors, in its discretion, will determine the nature, amount and timing of all distributions.

Assuming shares can be purchased at NSTR’s $1.85 close yesterday, after receiving the initial $1.80 per share, an investor will have $0.05 per share of capital invested for an upside of between $0.10 ($1.90 minus $1.80) and $0.30 ($2.10 minus $1.80) per share plus the possibility of receiving a further amount for NSTR’s non-cash assets, which we estimate could be as much as $0.16 per share. That seems like a favorable risk:reward ratio to us. The liquidation is still subject to stockholder approval, but we think NSTR presents a reasonable prospect for a good return in a short time frame.

[Full Disclosure:  We do not have a holding in NSTR. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Greenbackd Portfolio Q1 performance and update

March 1, 2009 marked the end of Greenbackd’s first quarter, so we thought we’d take the opportunity to update you on the performance of the Greenbackd Portfolio and the positions in the portfolio, discuss some changes in our valuation methodology since our first post and outline the future direction of Greenbackd.com.

First quarter performance of the Greenbackd Portfolio

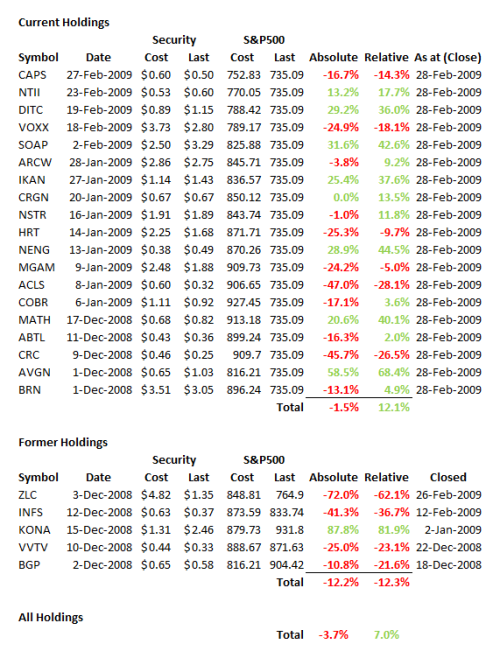
We get many questions about the content and performance of the portfolio. We had originally planned to report on a six-monthly basis, but we have now decided to report on a quarterly basis so that we can address these questions on a more frequent basis. Although it is still too early to determine how Greenbackd’s strategy of investing in undervalued asset situations with a catalyst is performing, we’ve set out below a list of all the stocks we’ve included in the Greenbackd Portfolio and the absolute and relative performance of each at the close on the last trading day in our first quarter, Friday, February 28, 2009:

greenbackd-portfolio-performance-2009-q13The absolute total return across the current and former positions as at February 28, 2009 was -3.7%, which was +7.0% higher than the S&P500’s return over the same periods. A negative return for the first period is disappointing, but we are heartened by the fact that we outperformed the market by a small margin.

You may have noticed something odd about our presentation of performance. The S&P500 index declined by 18.0% in our first quarter (from 896.24 to 735.09). Our -3.7% performance might suggest an outperformance over the S&P500 index of +14.3%. We calculate our performance on a slightly different basis, recording the level of the S&P500 index on the day each stock is added to the portfolio and then comparing the performance of each stock against the index for the same holding period. The Total Relative performance, therefore, is the average performance of each stock against the performance of the S&P500 index for the same periods. As we discussed above, the holding period for Greenbackd’s positions has been too short to provide any meaningful information about the likely performance of the strategy over the long term (2 to 5 years), but we believe that the strategy should outperform the market by a small margin.

Greenbackd’s valuation methodology

We started Greenbackd in an effort to extend our understanding of asset-based valuation described by Benjamin Graham in the 1934 Edition of Security Analysis. Through some great discussion with our readers, many of whom work in the fund management industry as experienced analysts or even managing members of hedge funds, we have had the opportunity to refine our process. We believe that what started out as a pretty unsophisticated application of Graham’s liquidation value methodology has evolved into a more realistic analysis of the balance sheet and the relationship of certain disclosures in the financial statements to asset value. We’re not yet ready to send it into space, but we believe our analyses are now qualitatively more robust than when we started and that has manifest itself quantitatively in better performance (more on this below).

The two main differences between our early analyses and our more recent ones are as follows (these are truly cringe-worthy, but that’s why we undertook the exercise):

  1. We didn’t take account of the effect of off-balance sheet arrangements and contractual obligations. This caused us to enter into several positions we should have avoided, including BGP and VVTV.
  2. We were using overly optimistic estimates for the recovery rates of assets in liquidation. For example, we started using 50% of Gross PP&E. We now use 20% of Net PP&E. We now apply Graham’s formula as the base case and deviate only when we believe that Graham’s formulation doesn’t reflect reality.

The effect of these two broad errors in analysis was to create several “false positives,” which is to say that we added stocks to the portfolio that wouldn’t have passed our current, more rigorous standards. The performance of those “false positive” stocks has been almost uniformly negative, and dragged down the performance of the portfolio. As an exercise, we went back through all the positions we have opened since we started the site and applied our current criteria, which are more stringent and dour than our earlier standards. We found that we would not have opened positions in the following eight stocks:

  • BRN (-13.1% on an absolute basis and +4.9% on a relative basis)
  • BGP (-10.8% on an absolute basis and -21.6% on a relative basis)
  • COBR (-17.1% on an absolute basis and +3.6% on a relative basis)
  • HRT (-25.3% on an absolute basis and -9.7% on a relative basis)
  • KONA (+87.8% on an absolute basis and +81.9% on a relative basis)
  • MGAM (-24.2% on an absolute basis and -5.0% on a relative basis)
  • VVTV (-25.0% on an absolute basis and -23.1% on a relative basis)
  • ZLC (-72.0% on an absolute basis and -61.1% on a relative basis)

It seems we got lucky with KONA, but the performance of the balance of the stocks was wholly negative. The performance across all stocks listed above was -12.5% on an absolute basis and -3.9% on a relative basis. Excluding these eight stocks from our portfolio (i.e. treating the portfolio as if we had not entered into these positions) would have resulted in a slightly positive absolute return of +0.7% and a relative performance over the S&P500 of +12.5%. This is a compelling reason to apply the more dour and rigorous standards.

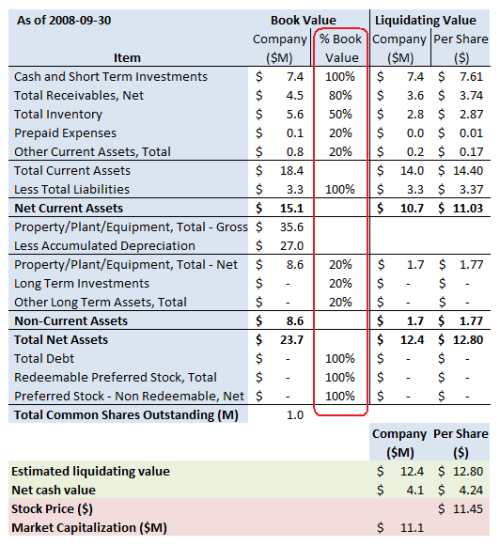
We like to think we’ve now learned out lesson and the more dour and rigorous standards are here to stay. Set out below is an example balance sheet summary (for Chicago Rivet & Machine Co. (AMEX:CVR)) showing our present base case discounts from book value (circled in red):

example-summary-2

Readers will note that these are the same base case discounts from book value suggested by Benjamin Graham in the 1934 Edition of Security Analysis, more fully described in our Valuing long-term and fixed assets post under the heading “Graham’s approach to valuing long-term and fixed assets.” Why we ever deviated from these standards in the first place is beyond us.

Update on the holdings in the Greenbackd Portfolio

Leading on from our discussion above, four of the stocks we picked using the initial, overly optimistic criteria no longer meet our more stringent standards but haven’t yet been removed from the portfolio. We’re going to take our medicine now and do just that. To make it clear, these stocks aren’t being removed because the value has deteriorated, but because we made a mistake adding them to the portfolio in the first place. As much as we’d like to treat these positions as void ab initio (“invalid from the beginning”), we’re not going to do that. We’ve made a full accounting of the impact they’ve had on the portfolio in the First quarter performance of the Greenbackd Portfolio section above, but we don’t want them affecting our future performance. The stocks to be removed from the Greenbackd Portfolio and their absolute and relative returns are as follows:

  • BRN (-13.1% on an absolute basis and +4.9% on a relative basis)
  • HRT (-25.3% on an absolute basis and -9.7% on a relative basis)
  • MGAM (-24.2% on an absolute basis and -5.0% on a relative basis)
  • COBR (-17.1% on an absolute basis and +3.6% on a relative basis)

We’ll provide a more full discussion of where we went wrong with these stocks at a later date, but suffice it to say for present purposes that all were errors from the second bullet point in the Greenbackd’s valuation methodology section above (i.e. overly optimistic estimates for the recovery rates of assets in liquidation).

There are fifteen stocks remaining in the Greenbackd Portfolio:

Eight of these positions (ABTL, ACLS, ARCW, CAPS, CRC, CRGN, NSTR, and VOXX) are trading at or below our nominal purchase price and initial valuations. The remaining seven positions (AVGN, DITC, IKAN, MATH, NENG, NTII, and SOAP) are trading above our intial purchase price but are still at varying discounts to our valuations. We’ll provide a more full update on these positions over the course of this week.

The future of Greenbackd.com

We are going to trial some small changes to the layout of the site over the next few weeks. We’ve already made the first change: the newest comments now appear at the top of the list. We’ll also be amalgamating some pages and adding some new ones, including a page dedicated to tracking the portfolio with links to the analyses. We’re also considering some options for generating income from the site. At the moment, Greenbackd is a labor of love. We try to create new content every week day, and to get the stock analyses up just after midnight Eastern Standard Time, so that they’re available before the markets open the following day. More than 80% of the stocks that are currently trading at a premium to the price at which we originally identified them (NTII, SOAP, IKAN, DITC, NENG, MATH and AVGN) traded for a period at a discount to the price at which we identified them. This means that there are plenty of opportunities to trade on our ideas (not that we suggest you do that). If you find the ideas here compelling and you get some value from them, you can support our efforts by making a donation via PayPal.

We look forward to bringing you the best undervalued asset situations we can dig up in the next quarter.

Read Full Post »

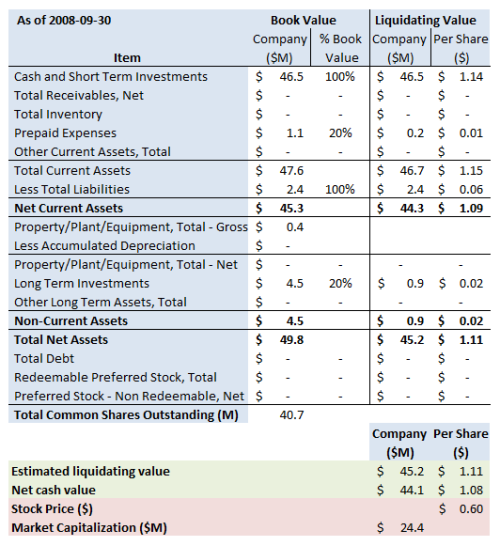
OrthoLogic Corporation (NASDAQ:CAPS) is a little unusual for us. While it trades below its net cash value and Biotechnology Value Fund (BVF) has disclosed a 13.42% holding, BVF’s holding is passive. At CAPS’s $0.60 close yesterday it has a market capitalization of $24.4M. We estimate the net cash value to be 80% higher at $1.08 per share. CAPS’s cash burn rate is quite high relative to its net cash position, so rapid steps need to be taken for this to be a profitable investment. We think that BVF is a good bet, so we’re adding CAPS to the Greenbackd Portfolio.

About CAPS

CAPS is a development stage biotechnology company focused on the development and commercialization of the synthetic peptides Chrysalin (TP508) and AZX100. Effective October 1, 2008, OrthoLogic Corp. is known and doing business as Capstone Therapeutics. The company’s investor relations website is here.

The value proposition

The summary of our estimate for the company’s liquidation value is set out below (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):
caps-summary

Note that we have used the September 10Q. CAPS’s most recent filings indicate that cash is actually $48M (see slide 13), but we don’t know what the rest of the balance sheet looks like. The presentation also gives cash burn guidance this year of $14M to $16M.

The company also included the following in its 10Q, which seems to indicate a shift to cash preservation:

We announced that we have no immediate plans to re-enter clinical trials for Chrysalin-based product candidates and a strategic shift in our development approach to our Chrysalin Product Platform. We currently intend to pursue development partnering or licensing opportunities for our Chrysalin-based product candidates, a change from our previous development history of independently conducting human clinical trials necessary to advance our Chrysalin-based product candidates to market. We will continue to explore Chrysalin’s therapeutic value in tissues and diseases exhibiting endothelial dysfunction as well as the science behind and potential of Chrysalin. We will also continue research and development expenditures for further pre-clinical studies supporting multiple indications for AZX100 and plan to continue AZX100 dermal scarring human clinical trials.

Off-balance sheet arrangements and Contractual obligations

There is no discussion in the September 10Q about CAPS’s off-balance sheet arrangements or contractual obligations.

The catalyst

Given that BVF has filed a 13G notice, which indicates a passive investment, we’re not entirely sure what BVF has planned for CAPS. It’s possible that it is simply a passive holding. We’re reasonably comfortable following BVF into CAPS because of their efforts with Avigen Inc (NASDAQ:AVGN) and Neurobiological Technologies Inc (NASDAQ:NTII).

CAPS has been undertaking a stock repurchase program since March 5, 2008. At September 30, 2008, the company had repurchased 1.1.M shares of its common stock, at a total cost of $1.0M, and had allocated approximately a further $1.1M to fund possible future stock repurchases. We don’t know the status of the buy-back at this time.

Conclusion

At its $0.60 close yesterday, CAPS is trading at 55% of our estimate of its $1.08 per share net cash value. The risk for this investment – as it is for all of these types of investment – is that CAPS dissipates its cash before it or BVF can salvage that value. Management is taking steps to reduce its cash burn and repurchase undervalued stock, which is encouraging. Perhaps this is what BVF has seen, and the reason BVF hasn’t filed a 13D notice. We think that BVF is a good bet, so we’re adding CAPS to the Greenbackd Portfolio.

CAPS closed yesterday at $0.60.

The S&P500 Index closed yesterday at 752.83.

Hat tip to ef.

[Full Disclosure:  We do not have a holding in CAPS. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »
Axcelis Technologies Inc (NASDAQ:ACLS) has announced that it has agreed to sell its 50% interest in SEN Corporation, its joint venture with Sumitomo Heavy Industries, Ltd. (SHI) to SHI for Y13 billion, or approximately $133 million, in cash. This is an outstanding achievement by ACLS management under difficult conditions. The sale will provide the liquidity necessary to meet the $85M due to the holders of the company’s 4.25% Convertible Senior Subordinated Notes, upon which ACLS defaulted in January.

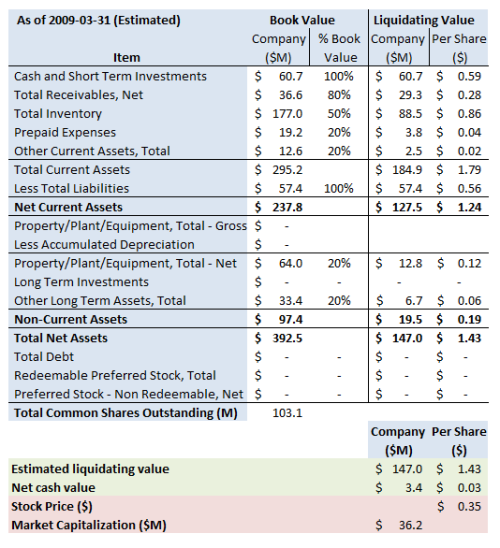
We started following ACLS on January 8 this year because it is an undervalued asset play with an activist investor, Sterling Capital Management, holding 10.7% of its outstanding stock. In our initial post we estimated ACLS’s liquidating value at $134.9M, or $1.31 per share. Assuming the sale is completed, we estimate ACLS’s liquidating value to be slightly higher at $147M or $1.43 per share, which is more than 300% higher than its close yesterday of $0.35.

The value proposition updated

ACLS is generating substantial and increasing operating losses, reaching a $22.8M nadir for the September quarter (see the September 10Q here). We have adjusted the September 10Q balance sheet to account for the sale of the SEN JV and to back out several other payments and projected it forward to March (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

acls-summary-sen-sale1This summary balance sheet assumes that the $133M to be received in March 2009 from the sale of SEN is used to pay off the notes first (approximately $85M) with the remainder added to cash. We have backed out a further $15M in termination payments from cash. This summary balance sheet also assumes that ACLS burns an additional $22M in cash in the current quarter. The company is still making substantial operating losses that have widened over the last five quarters, so these amounts are likely to be substantial on an ongoing basis.
The press release

ACLS has not yet filed an 8K but the press release is as follows (via Tradingmarkets.com):

Axcelis Technologies, Inc. (Nasdaq:ACLS) today announced that it has entered into a Share Purchase Agreement in which Sumitomo Heavy Industries, Ltd. (“SHI”) will purchase Axcelis’ 50% interest in their joint venture, SEN Corporation, an SHI and Axcelis Company, (“SEN”), for Y13 billion, or approximately $133 million, in cash at current conversion rates. Axcelis and SHI each currently own 50% of SEN, a Japanese company that is licensed by Axcelis to manufacture and sell certain implant products in Japan.

It is anticipated that the transaction between Axcelis and SHI will be completed on March 31, 2009. Axcelis will use a portion of the proceeds from the sale of its SEN interests to meet its obligations under its 4.25% Convertible Senior Secured Subordinated Notes, which were due in January. Pending the closing, the trustee for the notes has agreed to stand down on litigation filed in connection with Axcelis’ default on the notes.

Mary Puma, Chairman and CEO of Axcelis, said: “This transaction serves the best interests of Axcelis shareholders as it enables us to fulfill our senior debt obligations and gives us greater financial flexibility during this difficult economic climate and semiconductor industry downturn. Axcelis will continue to fully focus its efforts on tight cash and cost controls and on developing and selling innovative products like our Optima implanters and Integra dry strip tools, both of which have received strong customer reviews. With these products, Axcelis believes that we can compete and gain market share once demand for semiconductor equipment returns.”

As part of the transaction, at the closing Axcelis and SEN will enter into cross licenses that will allow the two companies to continue to use certain patents and technical information owned by the other to make and sell ion implant systems on a worldwide, royalty-free, perpetual basis. Axcelis’ license to SEN would not include patents, licenses, or technical information developed by Axcelis for the Optima HD, Optima XE, or any non-implant products. The transaction will terminate all existing agreements among Axcelis, SHI and SEN relating to the SEN joint venture.

More information can be found in the Form 8-K that Axcelis will file with the Securities and Exchange Commission at http://www.sec.gov.

Hat tip to manny.

[Full Disclosure:  We have a holding in ACLS. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Trident Microsystems Inc (NASDAQ:TRID) has filed its results for the quarter ended December 31, 2008. While its earnings and operating cash flow have now turned negative, its liquidation value remains almost unchanged. In our original post we wrote that TRID is an undervalued net cash stock looking for a catalyst. We continue to think it’s a good candidate for an activist campaign for the following reasons:

  1. It’s large for a net cash stock: As its $1.32 close yesterday, the company has a market capitalization of $83M. That puts it into the strike zone for funds with around $100M under management.
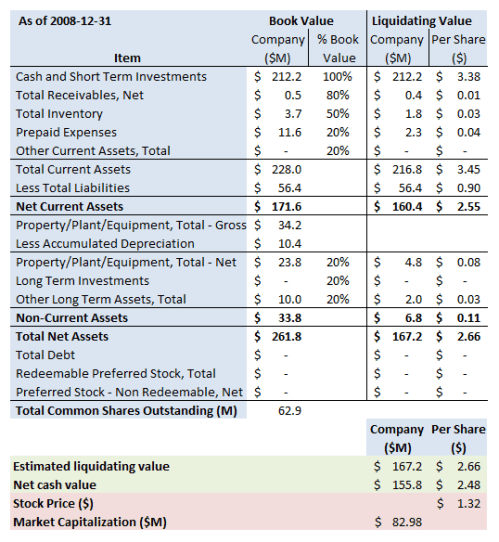
  2. It’s deeply undervalued: We estimate its liquidation value is around $167M or $2.66 per share, which is more than 100% higher than its close yesterday.
  3. Its value is predominantly cash: TRID is trading at half net cash value of approximately $155M or $2.48 per share.
  4. Its stock is liquid enough: According to TRID’s Google Finance page, the average volume for the stock is more than 530,000 shares per day. It traded more than 427,000 yesterday. With 63M shares on issue, an investor seeking ~5% of TRID needs a few more than 3M shares, which should be readily achievable in a reasonably short period of time.
  5. Management holds a vanishingly small number of shares and are net sellers.

We confess that – aside from the litigation and regulatory investigations into TRID’s granting of stock options – we can’t see the problem with TRID. Please leave a comment if you can see what we are missing.

The value proposition updated

TRID continues to boast an embarrassment of riches on its balance sheet (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

trid-summary-2009-12-31While TRID has burned through $18M of cash since our last post, it has reduced its liabilities by around the same amount, so its liquidation value remains unchanged. The slight reduction in liquidation value is a direct result of the additional stock on issue, which is the really TRID’s whole story: management takes the value that should belong to the shareholders.
Off-balance sheet arrangements and Contractual obligations

According to the 10Q, TRID has no off-balance sheet arrangements and its contractual obligations are relatively modest $11.6M, which includes total operating lease payments of $2.5M and total purchase obligations of $9.1M. There is also a long-term income tax payable of $20.1M but TRID is “unable to make a reasonably reliable estimate of the timing of payments in individual years beyond twelve months due to uncertainties in the timing of tax audit outcomes.”

Contingencies

The only real area of concern for us is the litigation and regulatory investigations into TRID’s granting of stock options. The following is extracted from the 10Q:

Shareholder Derivative Litigation

Trident has been named as a nominal defendant in several purported shareholder derivative lawsuits concerning the granting of stock options. The federal court cases have been consolidated as In re Trident Microsystems Inc. Derivative Litigation, Master File No. C-06-3440-JF. A case also has been filed in State court, Limke v. Lin et al., No. 1:07-CV-080390. Plaintiffs in all cases allege that certain of our current or former officers and directors caused it to grant options at less than fair market value, contrary to our public statements (including our financial statements); and that as a result those officers and directors are liable to us. No particular amount of damages has been alleged, and by the nature of the lawsuit no damages will be alleged against us. The Board of Directors has appointed a Special Litigation Committee, or SLC, composed solely of independent directors, to review and manage any claims that we may have relating to the stock option grant practices investigated by the SLC. The scope of the SLC’s authority includes the claims asserted in the derivative actions. In federal court, Trident has moved to stay the case pending the assessment by the SLC that was formed to consider nominal plaintiffs’ claims. In State court, Trident moved to stay the case in deference to the federal lawsuit, and the parties have agreed, with the Court’s approval, to take that motion off of the Court’s calendar to await the assessment of the SLC. We cannot predict whether these actions are likely to result in any material recovery by or expense to, Trident. We expect to continue to incur legal fees in responding to these lawsuits, including expenses for the reimbursement of legal fees of present and former officers and directors under indemnification obligations.

Regulatory Actions

The DOJ is currently conducting an investigation of us in connection with our investigation into our stock option grant practices and related issues, and we are subject to a subpoena from the DOJ. We are also subject to a formal investigation by the SEC on the same issues. We have been cooperating with, and continue to cooperate with, inquiries from the SEC and DOJ investigations. In addition, we have received an inquiry from the Internal Revenue Service to which we have responded. We are unable to predict what consequences, if any, that an investigation by any regulatory agency may have on it. Any regulatory investigation could result in our business being adversely impacted. If a regulatory agency were to commence civil or criminal action against us, it is possible that we could be required to pay significant penalties and/or fines and could become subject to administrative or court orders, and could result in civil or criminal sanctions against certain of our former officers, directors and/or employees and might result in such sanctions against us and/or our current officers, directors and/or employees. Any regulatory action could result in the filing of additional restatements of our prior financial statements or require that we take other actions. If we are subject to an adverse finding resulting from the SEC and DOJ investigations, we could be required to pay damages or penalties or have other remedies imposed upon us. The period of time necessary to resolve the investigation by the DOJ and the investigation from the SEC is uncertain, and these matters could require significant management and financial resources which could otherwise be devoted to the operation of our business. In addition, our 401(k) plan and its administration were audited by the Department of Labor but no further action was noted.

Indemnification Obligations

We indemnify, as permitted under Delaware law and in accordance with our Bylaws, our officers, directors and members of our senior management for certain events or occurrences, subject to certain limits, while they were serving at our request in such capacity. In this regard, we have received, or expect to receive, requests for indemnification by certain current and former officers, directors and employees in connection with our investigation of our historical stock option grant practices and related issues, and the related governmental inquiries and shareholder derivative litigation. The maximum amount of potential future indemnification is unknown and potentially unlimited; therefore, it cannot be estimated. We have directors’ and officers’ liability insurance policies that may enable us to recover a portion of such future indemnification claims paid, subject to coverage limitations of the policies, and plan to make claim for reimbursement from our insurers of any potentially covered future indemnification payments.

The catalyst?

Still none. No investors have disclosed an activist position in this stock and management still seem intent on helping themselves to big portions of options and restricted stock. Rather than pay dividends to long-suffering stockholders, they’ll retain the earnings to pump up the stock price, which helps with their options. The company could comfortably pay a special dividend of around $2.75 per share and still leave $40M of cash in the bank.

Conclusion

TRID’s board and senior management should be embarrassed that TRID is a perennial net net stock and now trades consistently below its net cash value. The market is sending a clear message when it values stock at less than net cash value. That they have the effrontery to gift themselves such huge helpings of stock and options in the face of such a message is astonishing. Even though it’s deeply undervalued, without some external pressure to allign management’s interests with its stockholders, TRID will remain that way. For the reasons we outlined above, TRID seems to us to be a prime candidate for an activist campaign. We can’t figure out why no activists are interested in this stock. What are we missing? Are we underestimating the impact of the litigation and regulatory investigations into TRID’s granting of stock options?

TRID closed yesterday at $1.32.

The S&P500 Index closed yesterday at 764.90.

[Full Disclosure:  We do not have a holding in TRID. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

The Zanett Group has increased its stake in MATH to 6.58% according to its most recent Schedule 13D amendment.

We’ve been following MATH since December last year when it was trading at $0.68. We initiated the position because MATH is a net cash stock with two substantial stockholders lobbying management to liquidate. The stock is up 19% to $0.87 yesterday, giving it a market capitalization of $8.0M. We estimate MATH’s liquidation value still to be more than 80% higher at $14.4M or $1.57 per share. That value is predominantly cash and short term investments and doesn’t take into account any further value that the sale of the FPOA technology and intellectual property may yield. The two activist investors, Mr. Zachary McAdoo of The Zanett Group and Mr. Salvatore Muoio of S. Muoio & Co., have been urging MATH’s board to consider liquidation rather than a merger. MATH’s board seems to agree, twice rejecting unsolicited merger proposals, suspending the company’s operations and exploring “strategic alternatives, which could include merger, acquisition, increasing operations in another structure or liquidation.”

The Zanett Group’s most recent share purchases were undertaken between January 22 and February 19 this year at prices between $0.81 and $0.90.

[Full Disclosure: We do not have a holding in MATH. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only.]

Read Full Post »

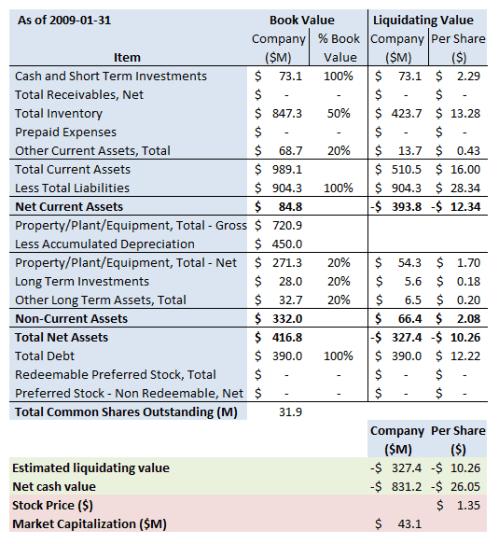
Zale Corporation (NYSE:ZLC) has released its results for the quarter to January 31, 2009. After reviewing the results, we have significantly reduced our original estimate for the company’s liquidating value since we initiated the position at $4.82 on December 3, 2008. Our initial analysis of ZLC’s balance sheet was overly optimistic. We’ve now applied more dour assumptions to ZLC’s results and, as a result, we’ve decided to close the position.

We started following ZLC believing it to be an undervalued asset situation. With former Chairman of the SEC turned activist investor, Richard Breeden of Breeden Capital Management LLC, holding two seats on the board, we thought it looked like a reasonable opportunity. At its $4.82 closing price on December 3, 2008 the company had a market capitalization of $154M. We estimated ZLC’s liquidation value at that time to be around $243M or $7.63 per share. After reviewing ZLC’s Q2 financial results and applying more dour assumptions for the value of the assets in liquidation, we now believe there is a risk that ZLC has no value in liquidation.

The value proposition updated

Set out below is our summary analysis of the balance sheet (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

zlc-summary-2009-q2Conclusion

At its $1.35 close yesterday, ZLC has a market capitalization of just $43M. When we started coverage in December last year, ZLC traded at $4.82 and had a market capitalization of $154M. Our ZLC position is down a punishing 72% on an absolute basis. The S&P 500 Index closed at 848.81 on December 3, 2008 and closed yesterday at 764.90. That’s a return of -9.9% for the index and means we’re off 62.1% on a relative basis, which is still very disappointing. The simple fact is that this was an unforced error. Our original analysis of ZLC was overly optimistic. We’ve been applying more dour assumptions about the recovery values of assets in liquidation to our most recent analyses. If we had been applying the more dour assumptions at the time we made our original assessment of ZLC, we would not have initiated the position.

[Full Disclosure:  We do not have a holding in ZLC. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

Biotechnology Value Fund (BVF) has extended its tender offer for the outstanding shares of Avigen Inc (Nasdaq: AVGN).

We’ve been following AVGN (see archived posts here) because it’s a net cash stock (i.e. it’s trading at less than the value of its cash after deducting all liabilities) and specialist biotechnology activist fund BVF has been pushing it to liquidate and return its cash to shareholders. MediciNova Inc (NASDAQ:MNOV) has made an offer for AVGN that we think represents a clever way for AVGN’s stockholders to receive cash equivalent to that which they would receive in a liquidation (less $7M to be paid to MNOV) with the possibility for “an extraordinary, uncapped return” if MNOV is successful post-merger. We estimate AVGN’s cash at around $1.22 per share (BVF estimates $1.20 per share), which is around 20% higher than AVGN’s $1.01 close yesterday.

The full text of BVF’s press release is reproduced below:

BVF Acquisition LLC (the “Purchaser”), an affiliate of Biotechnology Value Fund L.P. (“BVF”), which has commenced a cash tender offer to purchase all of the outstanding shares of Avigen, Inc. (Nasdaq: AVGN) (“Avigen”) for $1.00 per share, announced today that it has extended the expiration date for the tender offer to 6:00 p.m., New York City time, on Friday, March 6, 2009. The tender offer was previously set to expire at 12:00 midnight, New York City time, on Monday, February 23, 2009. As of the close of business on February 20, 2009, a total of 1,132,192 shares had been tendered in and not withdrawn from the offer, which together with the shares owned by BVF and affiliates, represents approximately 33% of the total shares outstanding of Avigen.

[Full Disclosure: We have a holding in AVGN. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only.]

Read Full Post »

CuraGen Corporation (NASDAQ:CRGN) has announced that it is considering strategic alternatives to enhance shareholder value including selling or licensing CR011, acquiring additional assets or business lines, or selling the company.

We started following CRGN on January 20 this year because it is a net cash stock with an investor, DellaCamera Capital Management, disclosing a 5.6% holding in January. We estimate CRGN’s net cash value to be around $62M or $1.07 per share. The company is not generating any operating cash flow as it is a “biopharmaceutical development company,” so the challenge for DellaCamera Capital Management is to persuade the company to pay a special dividend or liquidate before it dissipates its remaining cash.

The company’s press release (via Earth Times) is as follows:

CuraGen Corporation (Nasdaq: CRGN) announced today that it is undertaking a review of a broad range of strategic alternatives to enhance shareholder value.

Robert E. Patricelli, Chairman of the Board of CuraGen commented that “The Board believes that management is making exciting progress as CR011 moves through the current Phase II clinical trials and that it has taken the necessary actions over the past two years to ensure that CuraGen is a well capitalized organization in a difficult external financing environment. The Board further believes we should consider strategic alternatives that could enhance shareholder value. These alternatives range from selling or licensing CR011, to acquiring additional assets or business lines, to selling the company. The company will retain an investment bank to assist the Board with its strategic review. During our evaluation process, management will remain focused on executing our current business plan.”

Dr. Timothy M. Shannon, President and Chief Executive Officer, also announced that CuraGen has retained JSB-Partners to identify potential acquirers of CR011-vcMMAE. “In an ongoing multi-center study in heavily pretreated patients with breast cancer, CR011 is well tolerated and there is early evidence of activity. Our Phase II program in melanoma also continues to show promising activity”, commented Dr. Shannon. “The potential to move CR011-vcMMAE into more advanced development in both patients with breast cancer and patients with melanoma makes this a good time to seek strategic interest in the marketplace.”

There is no assurance that this process will result in any changes to the Company’s current business plans or lead to any specific action or transaction. While the process is underway, the Company does not intend or expect to disclose any developments regarding the process until, if ever, a definitive agreement is entered into or the board determines to terminate the process.

“We ended 2008 with $88 million of cash and investments on hand, have a clinically active attractive Phase II development asset, and over $500 million in net operating loss carryforwards (NOLs). Yet, our stock price does not reflect the intrinsic value of our assets and we continue to trade at a deep discount to our cash.” commented Dr. Shannon. “We seek to address these value disconnects through the strategic review process.”

The Company also recently completed a privately negotiated transaction with a holder of the Company’s 4% Convertible Subordinated Notes due February 2011 (the “2011 Notes”) in which the Company retired a total of $4.8 million of the 2011 Notes for an aggregate purchase price of $3.8 million or a 21% discount off of face value. This transaction added $1.0 million of net cash to the Company’s balance sheet. The Company now has $14.1 million of the 2011 Notes outstanding. The Company’s burn guidance for the first half of 2009 remains unchanged at $7.0 to $8.0 million and the Company now expects to end the second quarter of 2009 with between $76 and $77 million of cash and investments.

[Full Disclosure:  We do not have a holding in CRGN. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

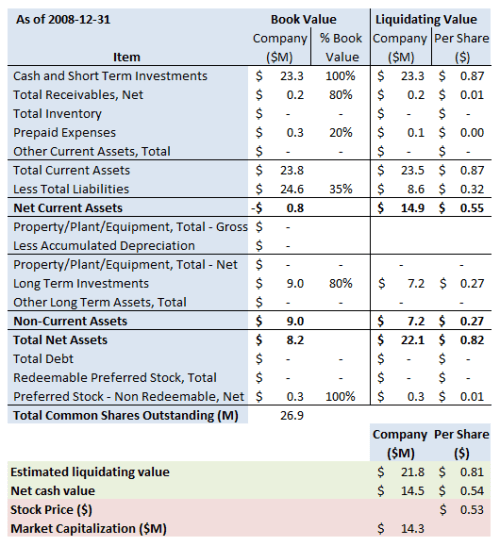
Neurobiological Technologies Inc (NASDAQ:NTII) is a particularly interesting play. Prima facie, it appears to be a cash-burning biotechnology stock trading at a premium to its liquidating value. In other words, a stock we wouldn’t touch with a ten foot pole. On closer inspection, however, it becomes clear that NTII is trading at its net cash value, has other readily valuable assets and offers the possibility of substantial additional upside. At its $0.53 close on Friday, NTII has a market capitalization of just $14.3M, which is right on our $14.5M estimate for its net cash value. Our estimate for its liquidating value is around 50% higher at $21.9M or $0.81 per share with the possibility that it is significantly higher again. Three activist investors, Biotechnology Value Fund (BVF), Millennium Technology Value Partners and Highland Capital Management, hold approximately 45% of NTII’s outstanding stock and have called for its liquidation. We’re adding it to the Greenbackd Portfolio.

About NTII

NTII is a biopharmaceutical company historically focused on developing treatments for central nervous system conditions and other serious unmet medical needs. The company recently terminated development of its most advanced product candidate, ViprinexTM. The company has the right to receive royalty payments from the sales of Namenda (memantine HCL), an approved drug marketed for Alzheimer’s disease, and potential milestone and royalty payments from the development of XERECEPT, an investigational drug which has completed a Phase 3 clinical trial for the treatment of swelling associated with cerebral tumors. Additionally, NTII’s earlier stage pipeline includes rights to a protein in preclinical development for the treatment of Alzheimer’s disease. The company’s investor relations website is here.

The value proposition

NTII has no material ongoing operations as of December 2008. It continued to burn cash through the last quarter.  According to the most recent 10Q, however, its cash burn rate should now be “significantly curtailed since the Viprinex program for acute ischemic stroke was terminated in December 2008.” The summary of our estimate for the company’s liquidation value is set out below (the “Book Value” column shows the assets as they are carried in the financial statements, and the “Liquidating Value” column shows our estimate of the value of the assets in a liquidation):

ntii-summaryThere are two unusual elements in our summary balance sheet:

  1. Total Liabilities, carried in the balance sheet at $24.6M, have been adjusted down to 35% to remove $16M attributable to deferred revenue and warrant liability. We would not normally adjust the Total Liabilities at all. We have excluded these amounts from the Total Liabilities in this instance because the company “[does] not believe these items will ever require cash payments from us” (see Liquidity and Capital Resources in the most recent 10Q).
  2. Long Term Investments, carried in the balance sheet at $9M, have only been discounted by 20%, rather than our usual 80%. The Long Term Investments are predominantly AAA-rated auction rate securities (ARS) that continue to pay interest. The figure for the ARS in the balance sheet reflects the ARS’s purchase price less impairment charges of $1.6M at December 31, 2008. From the most recent 10Q:

Beginning in February 2008, failed auctions occurred throughout the ARS market, and since then all auctions for NTI’s ARS have been unsuccessful. While the credit rating of these securities remains high and the ARS are paying interest according to their terms, as a result of the potentially long maturity and lack of liquidity for ARS, the Company believes the value of the ARS in NTI’s portfolio has been impaired. During the fiscal year ended June 30, 2008, the Company recorded an impairment charge to reduce the carrying value of the ARS. The impairment charge was based on a model of discounted future cash flows and assumptions regarding interest rates. The Company has also recorded an unrealized loss of $1,360,000 on its ARS at December 31, 2008 based on a decrease in the estimated fair value since the impairment charge was initially recorded. Due to recent wide and rapid fluctuations in the credit markets, combined with the Company’s low forecasted operating expenses in comparison to its cash and investments balances, the Company believes the current fiscal year decline in estimated market price for the ARS to be temporary. The Company believes it has the ability to hold its ARS until recovery of the temporary decline in value. All other unrealized gains and losses were immaterial. The Company has classified its ARS as long-term at December 31, 2008, and all other investments are classified as short-term.

Accordingly, we believe that a 20% discount to the value of the ARS carried in the Long Term Investments is sufficient, if overly cautious.

XERECEPT®

NTII sold the rights to XERECEPT to Celtic Pharmaceuticals in 2005. Celtic Pharmaceuticals has continued to develop XERECEPT and recently announced that it has retained an investment bank to assist with the sale of XERECEPT. NTII is entitled to receive between 13% and 22% of the net proceeds received by Celtic Pharmaceuticals upon the sale of XERECEPT. We don’t know if the sale process will be successful or if NTII will receive any payment, but it does present the possibility of additional value to stockholders of NTII.

Off-balance sheet arrangements

According to the 10Q, NTII has “no off-balance sheet arrangements that have or are reasonably likely to have a current or future effect on our consolidated financial condition, changes in our consolidated financial condition, revenues or expenses, consolidated results of operations, liquidity, capital expenditures or capital resources.”

Contractual obligations

NTII’s noncancelable contractual obligations set out in its 10Q are as follows:

  • Active ingredient production/purification and operation of a snake farm. Raw venom of the Malayan pit viper was the starting material for the active ingredient in Viprinex, and was produced by Nordmark in Germany where Nordmark maintained a colony of snakes in a manufacturing facility. We agreed to make monthly payments to Nordmark for our supply of the active ingredient and for the fully burdened costs of operating the snake farm until such time as either 1) the agreement is terminated pursuant to specified terms or 2) commercial production commences. If the agreement is terminated by us prior to commercialization, we are required to make a termination payment of up to €2.8 million (or approximately $3.7 million at the December 31, 2008 exchange rate) to Nordmark. We have notified Nordmark of our intent to terminate the agreement and remove the snakes located at the facility. Under the terms of the agreement, we are responsible for specified operating costs of the facility as long as the snakes are at the facility. We have identified several reptile zoos willing to take snakes, and are in process of completing the arrangements for the transfer of the snakes. We cannot estimate the costs for this process, but we currently expect it to be completed by March 31, 2009.
  • Clinical Research Organizations. We had agreements in place with several Clinical Research Organizations for work needed on the clinical trials in various foreign countries. We generally paid the CROs on a monthly or quarterly basis for work as it was performed, and the terms of most of the agreements allow them to be cancelled with no obligations beyond the costs incurred by the CROs to the time of termination. Our CROs have closed down the clinical trial and are in the process of reconciling pass-through costs for the clinical trial and amounts we have paid compared to actual costs incurred. We have accrued expenses as of December 31, 2008 which we believe are appropriate under the agreements, and are holding further payments to the CROs until we are satisfied that all costs are justified under the agreements. We expect resolution with all CROs in the third or fourth quarter of our fiscal year ending June 30, 2009.
  • Medical facilities conducting the clinical trials. We generally pay medical facilities for each patient enrolled into our trials, and withhold a portion of total site compensation until all data required in the clinical trial protocol is received. The portion withheld is recorded as a liability in our consolidated financial statements. As we receive the final data from each site we authorize the release of the final payments called for under the agreements. We expect this process to be completed by March 31, 2009.
  • Data management. We pay outside service organizations on a monthly or quarterly basis for services related to managing the data collected from the clinical trial. We have recorded an accrued liability for the charges we expect to incur, and the service organizations are in process of reconciling the payments from NTI to the actual charges incurred. We expect this process to be completed by June 30, 2009.
  • License agreement for Viprinex. We have an exclusive worldwide license for all human therapeutic indications for Viprinex from Abbott. Under this license, we have an obligation to use commercially reasonable efforts to develop Viprinex for the treatment of acute ischemic stroke. If we do not use commercially reasonable efforts to develop Viprinex for stroke Abbott may reclaim rights to develop the product. While no license maintenance payments are required to Abbott, milestone payments of up to $2 million would be due upon various regulatory approvals of Viprinex, along with royalty payments based on worldwide Viprinex sales. In the event we sublicense the rights to Viprinex, additional payments may be due to Abbott based on the terms of the sublicense. We have the right to terminate the agreement upon providing 90 days notice to Abbott, and Abbott has the right to terminate the agreement only in the event of our breach. We presently do not intend to develop Viprinex further under the license from Abbott and expect rights will ultimately be returned under the terms of the agreement. Upon returning the rights to Abbott, we are also required to return all drug material, data and intellectual property to Abbott.
  • Employees. All of our employees are employed on an “at-will” basis.
  • Buck Institute for Age Research. We have entered into agreements with Buck for rights to preclinical proteins for the treatment of Alzheimer’s disease and Huntington’s disease. The research programs under these agreements may be extended annually and we have the right to terminate the agreements upon 60 days notice if we determine the research program objectives cannot be substantially met. In addition, we have certain milestone obligations to Buck in the event that specified research goals are met. We have notified Buck that we do not intend to extend the research program for Huntington’s disease, and are currently reviewing the Buck proposal for the second year of the Alzheimer’s disease research program.

While these contractual obligations are significant relative to NTII’s net assets, we believe that NTII’s interest income and the royalty revenue ($2m in the last quarter) should wash these obligations for the next 12 months, or at least reduce the cash burn rate to between $1M and $2M. The royalty ends in 2009.

The catalyst

Three large shareholders, BVF, Millennium Technology Value Partners and Highland Capital, hold 45% of NTII’s outstanding stock. BVF initiated its position in June last year, disclosing a 19.7% holding. According to a later 13D amendment,  BVF sent a letter on December 23, 2008 calling on NTII’s board:

…to exercise its fiduciary duty to shareholders by winding up NTII in order to return cash to shareholders as quickly and efficiently as possible. The letter explains that costs associated with a liquidation could be limited by immediate, decisive action because  [NTII]’s remaining assets are financial and passive in nature requiring negligible activity to manage. The letter calls on [NTII] to take immediate action to maximize shareholder value by returning capital to shareholders, consistent with its fiduciary duties, and to refrain from engaging investment bankers or other advisors (except for the sole purpose of winding up the company), whose self-interests would likely lead to a further drain of capital.

Samuel L. Schwerin (Managing Partner of Millennium Technology Value Partners) filed a 13D amendment on  January 6, 2009 disclosing a 7.7% holding (which includes the Millennium Technology Value Partners’ holdings disclosed below). Schwerin’s purpose for the filing is as follows:

On January 6, 2009, in the context of the failure of the clinical trial for Viprinex, [NTII]’s primary asset, Millennium Technology Value Partners delivered a letter urging [NTII] to take immediate and decisive action to monetize the remaining value of [NTII]’s assets for the benefit of its shareholders. The letter details Millennium’s belief that the only remaining course of action for [NTII]’s management and board to pursue is the immediate dissolution and liquidation of the company. Millennium has communicated to management that such dissolution should take the form of an immediate distribution of cash to shareholders, followed by an efficient and timely monetization of remaining assets in a manner designed to maximize proceeds to shareholders. Millennium’s letter further suggests that during nearly a dozen conversations between management of [NTII] and Millennium over the past year, management made assurances to Millennium that contingency liquidation plans had been developed in the event of failed Viprinex trials. Millennium expressed its strong belief that these plans should be implemented immediately and that there is no need, nor reason, to waste time or shareholder resources on advisors or to delay the liquidation process in order to explore risky alternative strategies, courses that Millennium believes are likely to result in further diminution of value for all shareholders.

Highland Capital disclosed a 17.6% holding in its original 13D notice filed January 9, 2009. According to the notice:

Highland Capital delivered a letter to NTII requesting the expeditious wind down of [NTII]’s business. In the letter, Highland Capital expressed its belief that, due to the failure of the Viprinex program, [NTII] has no incremental value as an ongoing concern. Highland Capital expressed a strong belief that the only way to return value to the shareholders is through liquidation of [NTII]’s assets. The letter notes that [NTII] is seeking to hire a new CEO and President, and that such action shows an intention to continue operations. Highland Capital believes that the Board should immediately decide to liquidate [NTII], and that hiring a new CEO and President is unnecessary if such action is to be taken.. Highland Capital expressly lists various assets, including cash, currently held by [NTII] which are all capable of near-term liquidation. Highland Capital asserts that it is [NTII]’s Board of Directors’ fiduciary duty to the public shareholders to liquidate these assets, wind down business, and return all proceeds to the public shareholders. Highland Capital expressed concern that the Board was considering “strategic options” to continue business which would result in the immediate degradation and eventual loss of all shareholder value.

Millennium Technology Value Partners disclosed a 3.7% holding in its original 13D filing dated January 23, 2009. Annexed to the filing was the following letter:

The Board of Directors of Neurobiological Technologies, Inc.
c/o Abraham E. Cohen, Chairman of the Board
2000 Powell Street, Suite 800
Emeryville, CA 94608

Dear Members of the Board:

As you know, on January 6, 2009 Millennium Technology Value Partners L.P. (“Millennium”) delivered a letter to the Board of Neurobiological Technologies, Inc. (“NTI” or the “Company”) urging it to take immediate and decisive action to monetize and distribute the Company’s remaining assets for the benefit of shareholders. We have since learned through a review of public filings and discussions with you that the Company has received correspondence from stockholders representing 65% of NTI shares expressing a similar point of view. This would appear to constitute a clear mandate from the stockholders of the Company for you to take immediate action to commence an orderly liquidation. We are disappointed that in the face of such an overwhelming directive from your stockholders, you are able to act other than with absolute immediacy to carry out the will of your constituency.

Over the past 14 months, management and members of the Board repeatedly assured Millennium that contingency plans involving liquidation had been developed and would be implemented immediately should Viprinex fail. Now that Viprinex has failed, we can’t help but wonder, where is the contingency plan and why hasn’t it been implemented? While we appreciate the Company’s January 13 announcement regarding the reduction of staff and the trimming of costs, the ultimate inaction on the Board’s behalf is alarming. Trimming costs merely lowers the cash burn and slows the rate of decline in shareholder value. It does not stop the decline, and more importantly, it does not seek to return maximum value to shareholders.

We are further concerned by discussions involving the potential engagement of financial advisors. As you know, financial and strategic advisors often require a considerable period of time to “evaluate strategic alternatives” and are compensated in such a way as to place an inherent bias against recommending liquidation, which in NTI’s case, is the best, and most immediate, course of action. There is no need, nor reason, to waste time or shareholder resources on advisors or to delay the liquidation process in order to explore risky alternative strategies, courses certain to result in further diminution of value for all shareholders, when the majority of the stockholders of the Company appear to have already made their views perfectly clear. The Board should understand that any action that it takes that would require the approval of its stockholders — other than the prompt liquidation of the Company — will not receive sufficient votes to pass. Accordingly, and by definition, any such attempts would clearly constitute a waste of corporate assets.

Recent discussions with management and members of the Board have further confirmed that “the process of exploring alternatives is ultimately most likely to conclude that liquidation is the best course of action for the shareholders of NTI.” Yet 37 days have passed since the failure of Viprinex, “the sole major asset of the Company,” without the Board communicating or enacting a plan designed to maximize shareholder value through the dissolution and liquidation of NTI assets. We have even gone so far as to outline a plan of liquidation to the Company that we believe could be approved by a substantial majority of the Company’s stockholders. In that plan, excess cash would be immediately distributed to shareholders, with the remaining assets to be liquidated in a timely and orderly manner over the coming months by a shareholder appointed fiduciary, with all proceeds being distributed directly to shareholders immediately upon receipt.

Should the Board have any question that the plan outlined above is in the best interests of shareholders, and that any attempts to pursue an alternative course of action would be over the objection of your stockholders, then we urge you to call a Special Meeting to allow the shareholders to reinforce our own conclusions and those suggested in correspondence from shareholders representing 65% of NTI stock.

To reiterate what we said in our January 6, 2009 letter and have repeated numerous times during our discussions with management, we believe that any action other than the immediate dissolution and liquidation of the Company is an irresponsible waste of corporate assets and will result in a severe impairment of shareholder value. We trust that the best interests of NTI shareholders continue to be of utmost importance to you, the members of the Board, and look forward to your prompt response. If either the Board or management has any questions about the appropriate liquidation plan and how best to implement it, we would welcome the opportunity to discuss it further.

With every day that you fail to take action, the value of the Company declines. We urge you to consider very carefully your primary obligations to your stockholders, and the consequences of your failure to honor these obligations.

Respectfully,

Samuel L. Schwerin
Managing Partner

Conclusion

At its $0.53 close on Friday, NTII is trading at its net cash value and around two-thirds of our estimate of its $0.81 per share liquidating value. The difference between our estimates for NTII’s net cash value and its liquidation value is the $9M in ARS, which we’ve discounted by 20% to $7.2M, and which the company believes will eventually yield full value. The possibility exists that the upside might be even greater if NTII receives a portion of the net proceeds paid to Celtic Pharmaceuticals upon a sale of XERECEPT. With stockholders representing 45% (note that Samuel L. Schwerin estimates 65%) of the outstanding stock of NTII calling for its liquidation, we feel the company will be under some pressure to accede and that should lead to a reasonably quick resolution. NTII is reminiscent of our position in Avigen Inc (NASDAQ:AVGN), which seems to be working out well. We’re adding it to the Greenbackd Portfolio.

NTII closed yesterday at $0.53.

The S&P500 Index closed yesterday at 770.05.

[Full Disclosure:  We do not have a holding in NTII. This is neither a recommendation to buy or sell any securities. All information provided believed to be reliable and presented for information purposes only. Do your own research before investing in any security.]

Read Full Post »

« Newer Posts - Older Posts »